UK business cash planning · Illustrative example
Find the usable cash inside a £320,000 balance
Reserve known commitments and stress-test delayed customer payments.
Money in
Opening bank balance: £320,000
Money out
Base planning surplus: £85,000
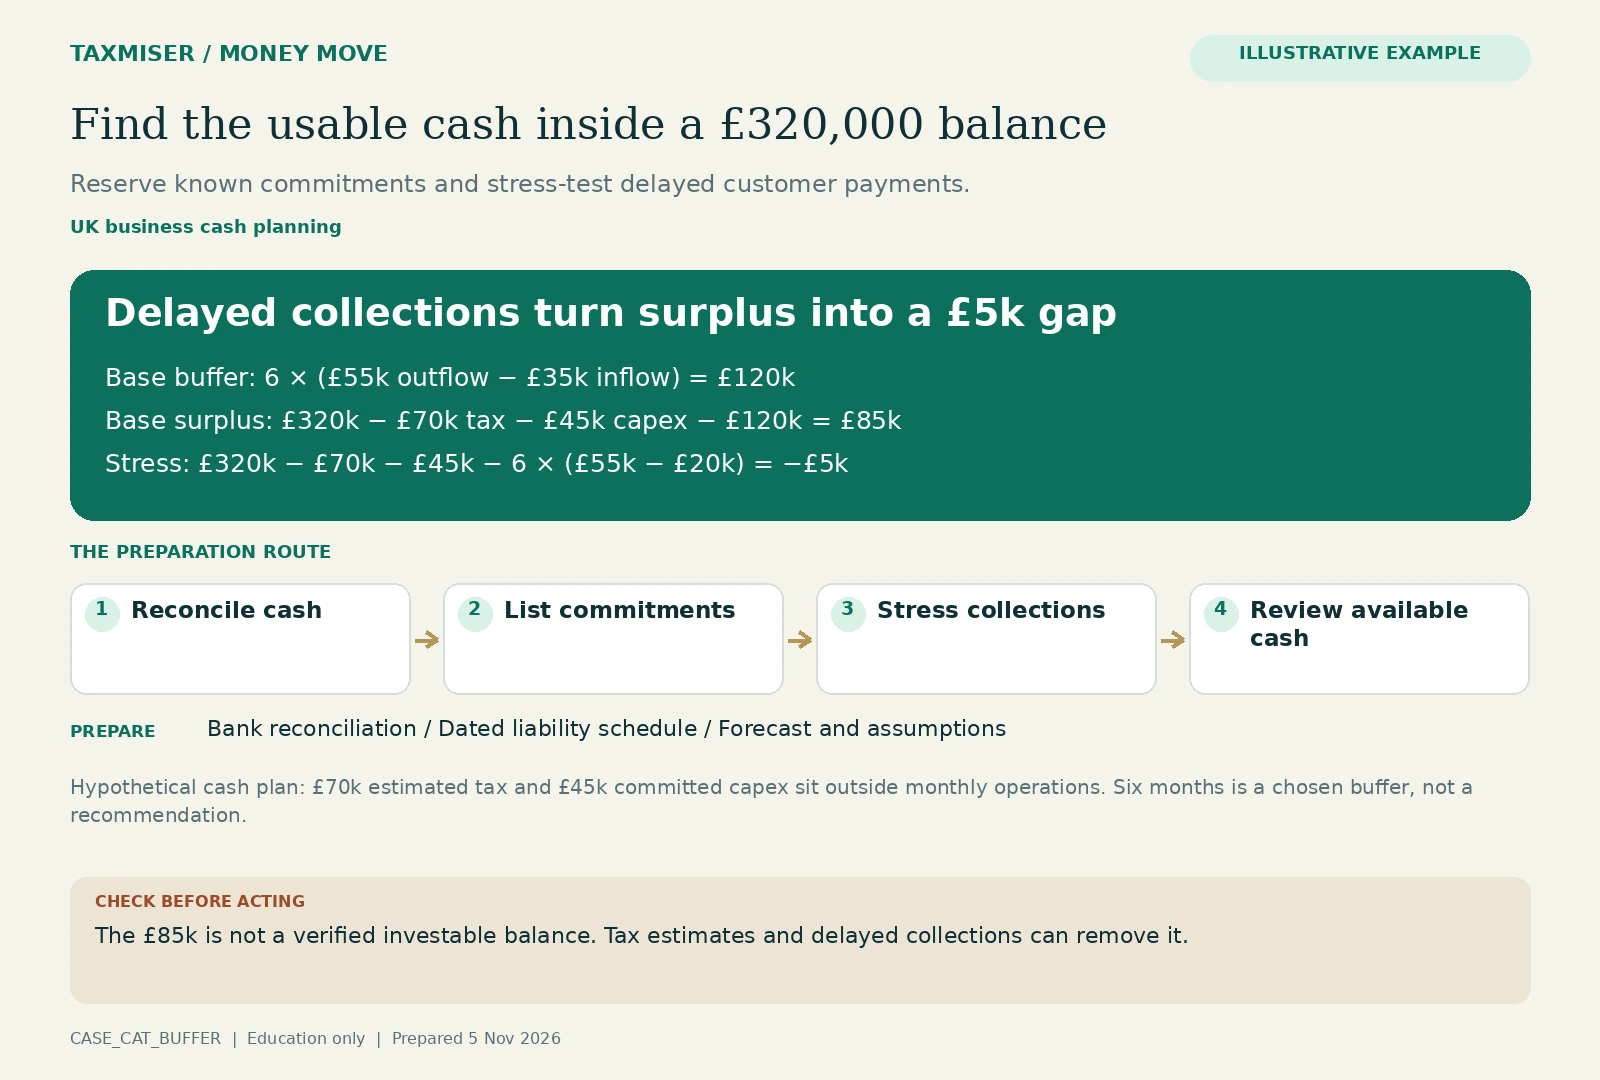
Delayed collections turn surplus into a £5k gap
- Base buffer: 6 × (£55k outflow − £35k inflow) = £120k
- Base surplus: £320k − £70k tax − £45k capex − £120k = £85k
- Stress: £320k − £70k − £45k − 6 × (£55k − £20k) = −£5k
Hypothetical cash plan: £70k estimated tax and £45k committed capex sit outside monthly operations. Six months is a chosen buffer, not a recommendation.
The £85k is not a verified investable balance. Tax estimates and delayed collections can remove it.
Steps
- Reconcile cash
- List commitments
- Stress collections
- Review available cash
Documents
- Bank reconciliation
- Dated liability schedule
- Forecast and assumptions
My brief
Write down how this applies to you. It saves to your account as you type.
Sign in as a member to save this to your account.
Sources
- Protecting cash flow and working capital, British Business Bank
- Company and accounting records, GOV.UK