Money moves
See the numbers before you move the money
Worked examples with the calculation, the documents and the risks side by side. Every figure is illustrative, and every rule links to its source.
Worked examples
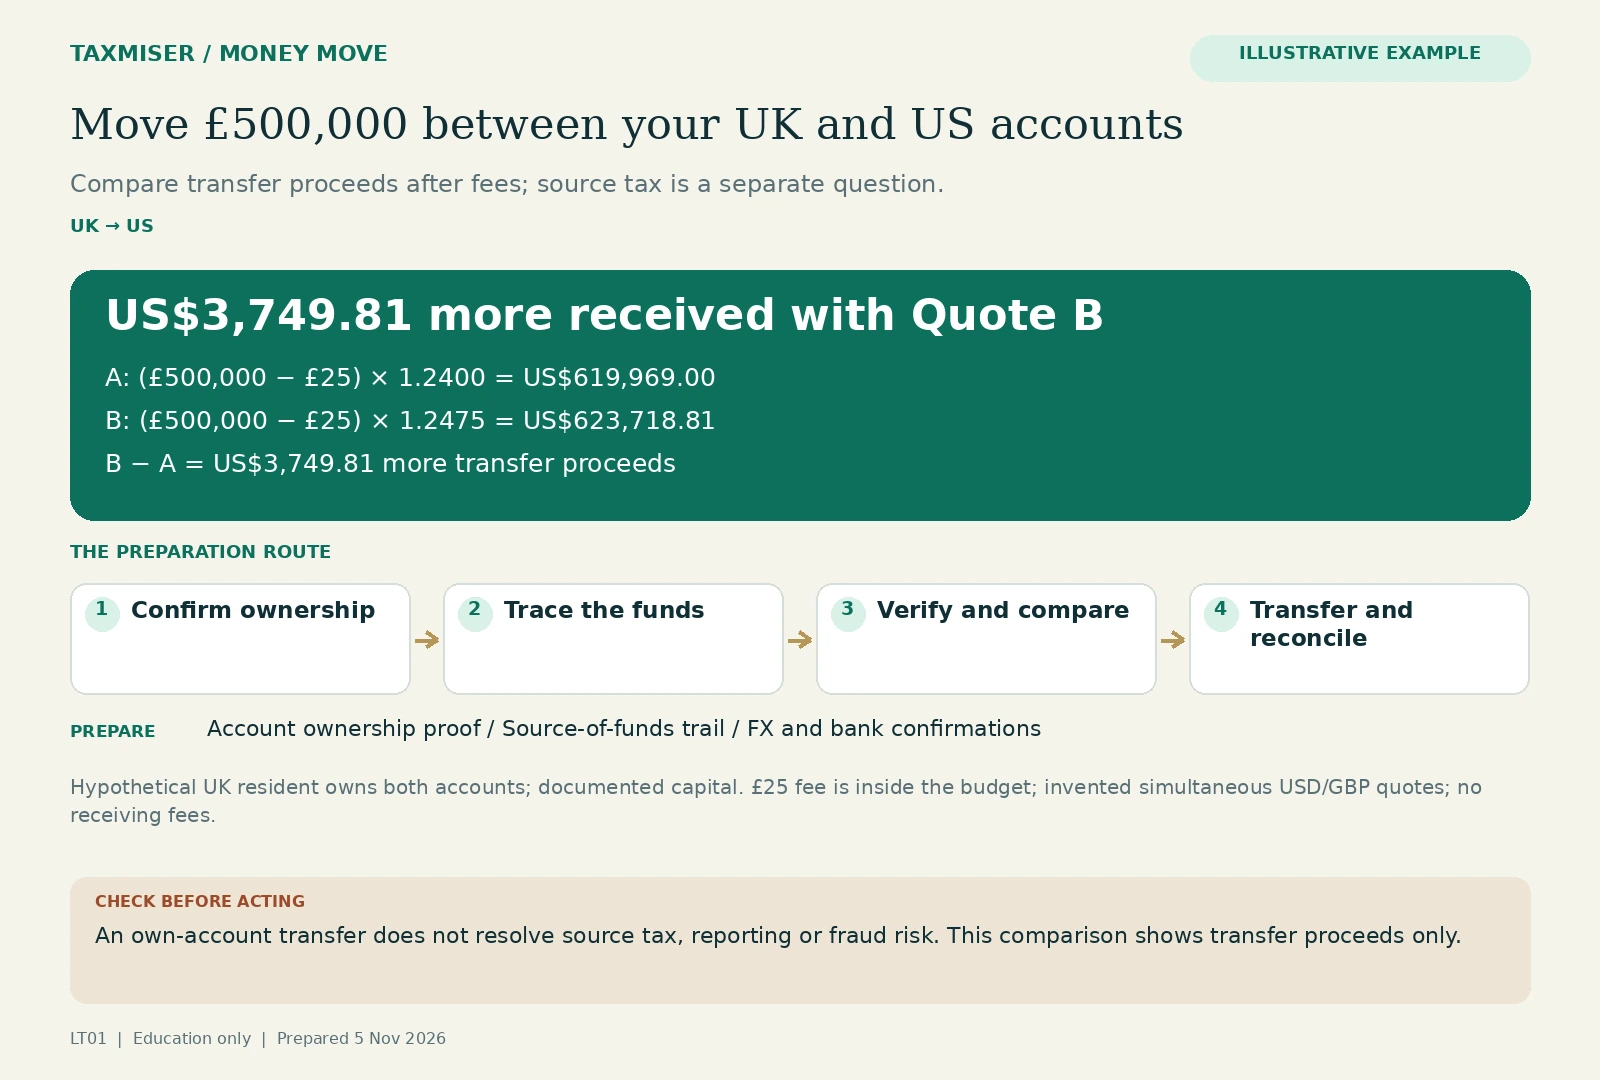 UK → US · Illustrative example
Move £500,000 between your UK and US accounts
Compare transfer proceeds after fees; source tax is a separate question.
US$3,749.81 more received with Quote B
See the steps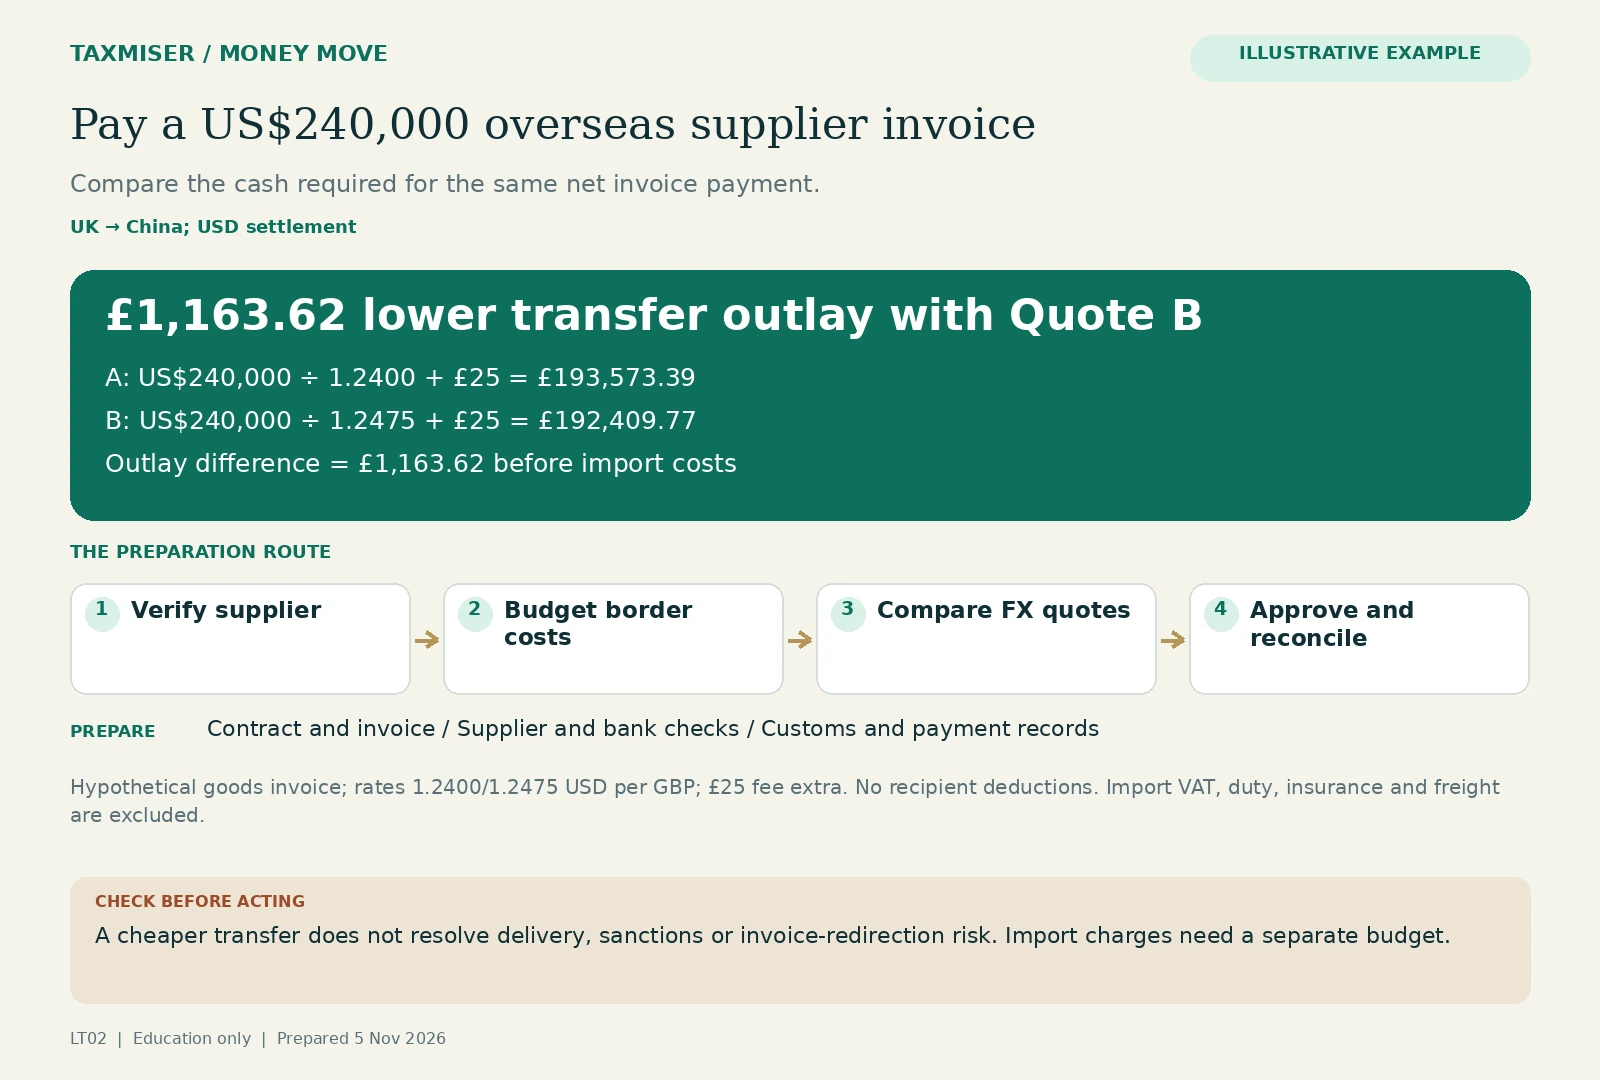 UK → China; USD settlement · Illustrative example
Pay a US$240,000 overseas supplier invoice
Compare the cash required for the same net invoice payment.
£1,163.62 lower transfer outlay with Quote B
See the steps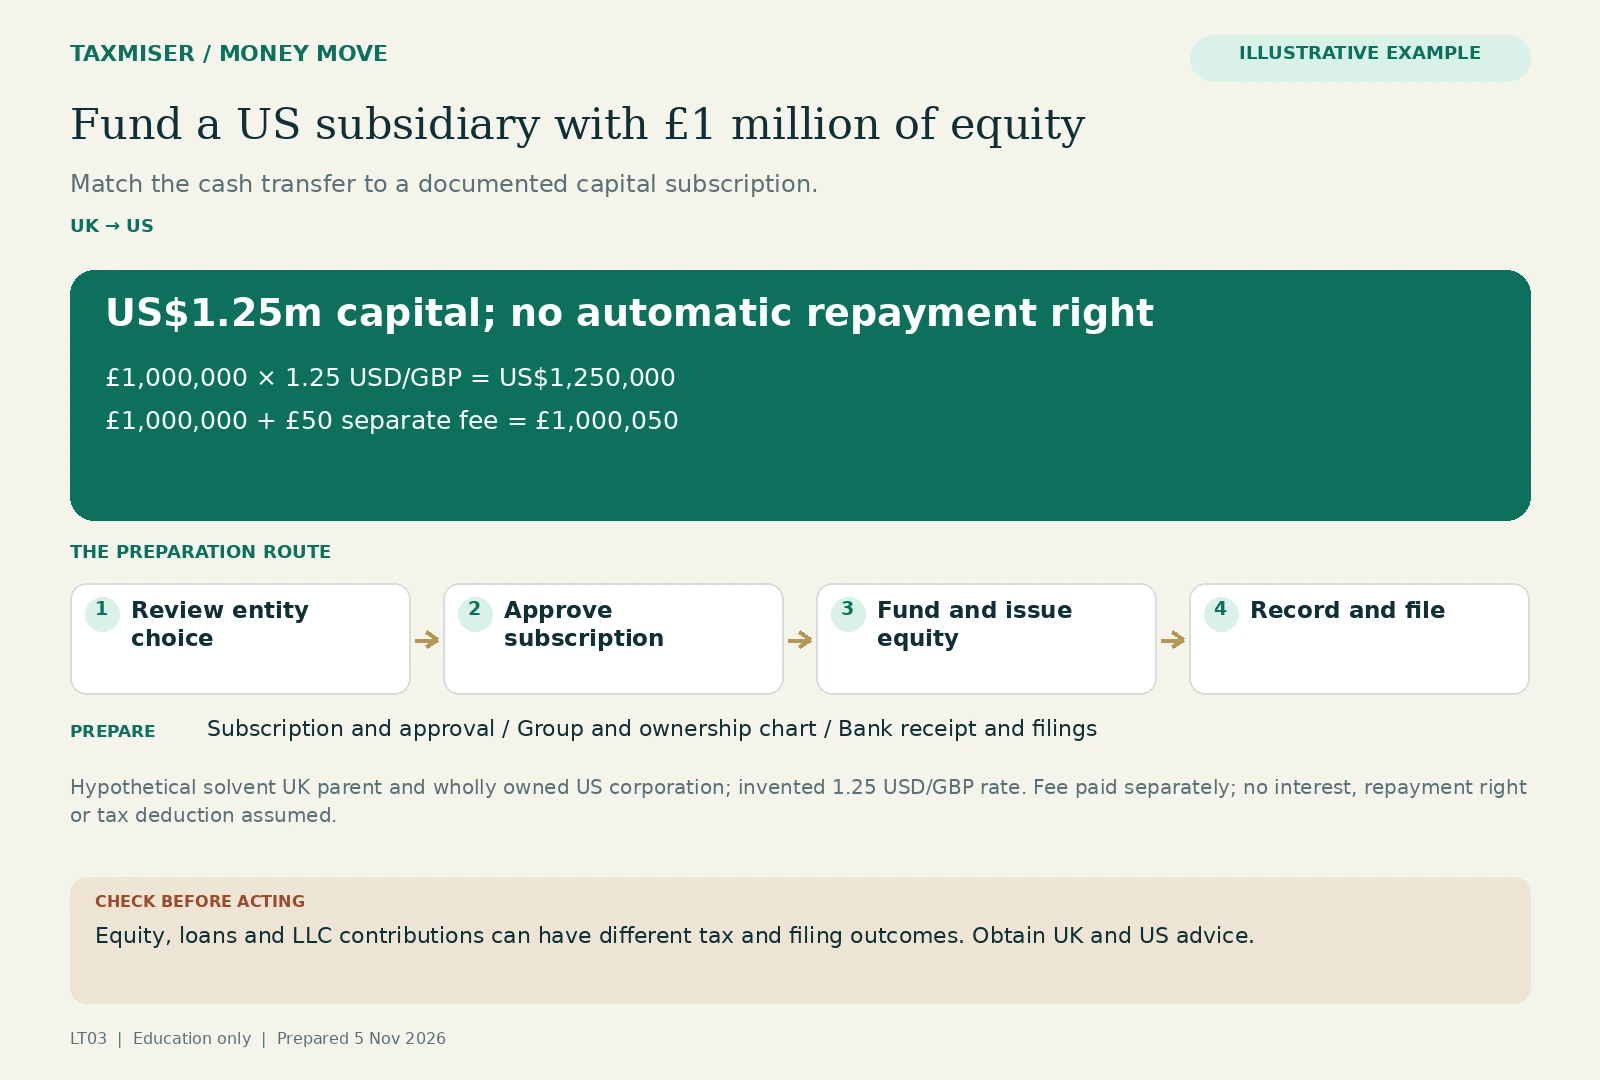 UK → US · Illustrative example
Fund a US subsidiary with £1 million of equity
Match the cash transfer to a documented capital subscription.
US$1.25m capital; no automatic repayment right
See the steps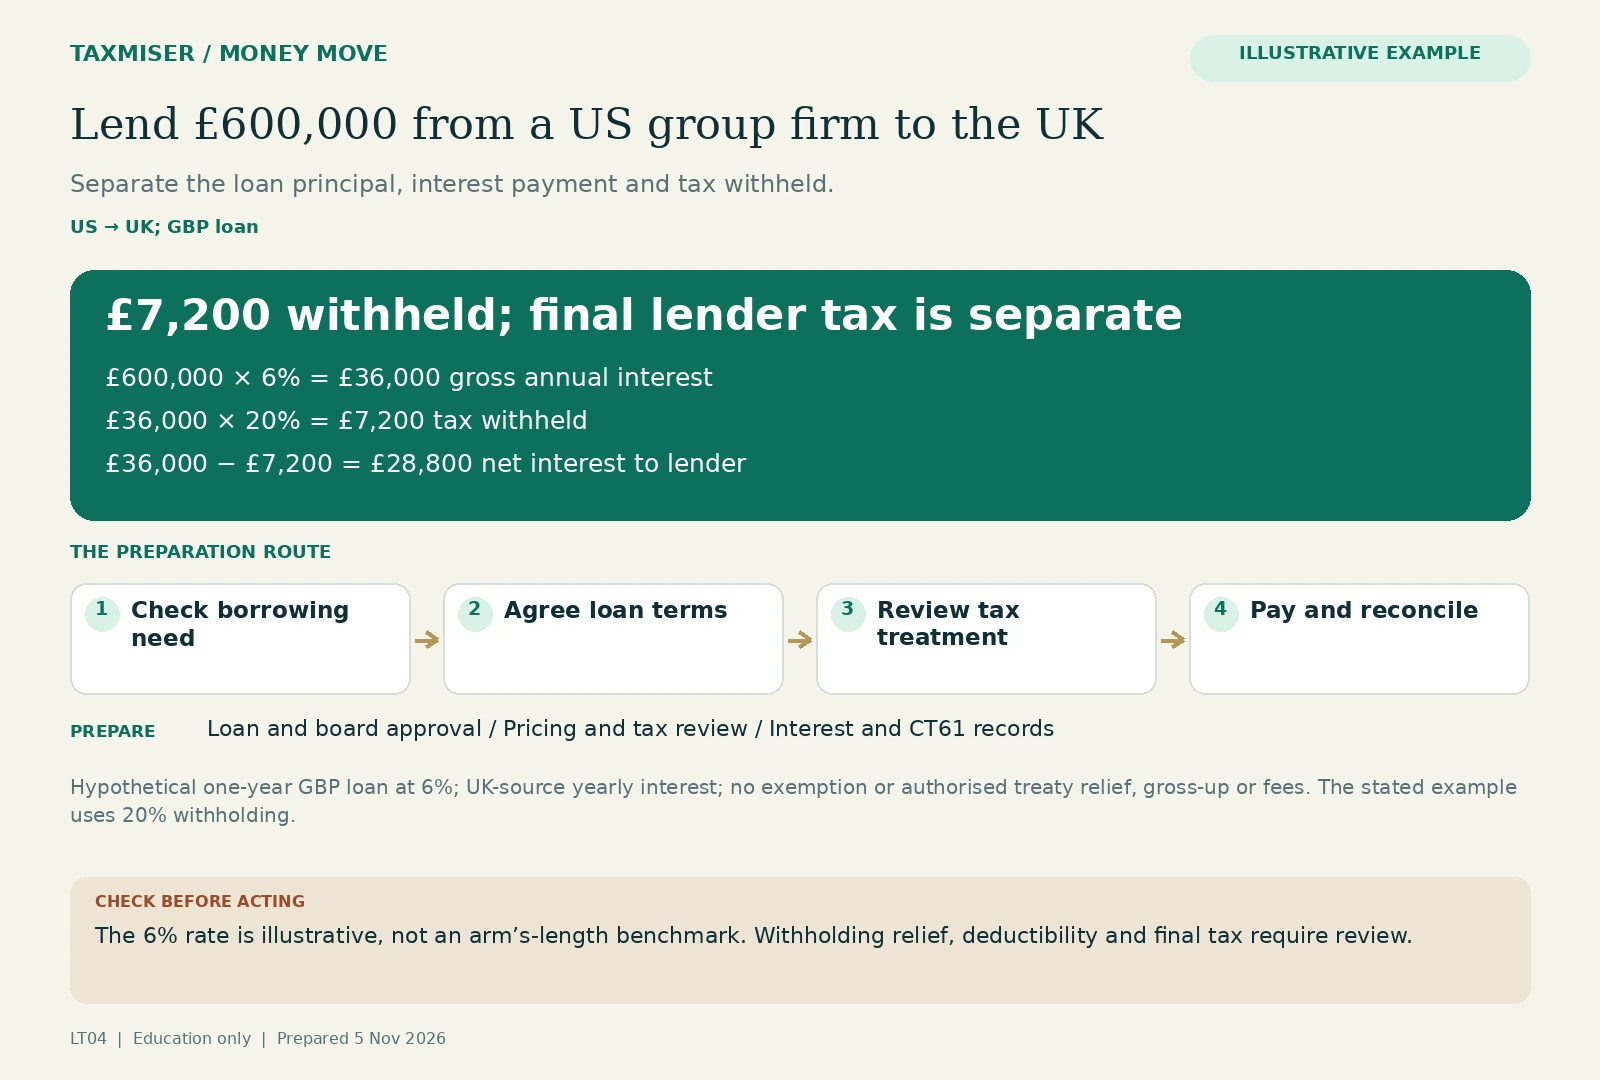 US → UK; GBP loan · Illustrative example
Lend £600,000 from a US group firm to the UK
Separate the loan principal, interest payment and tax withheld.
£7,200 withheld; final lender tax is separate
See the steps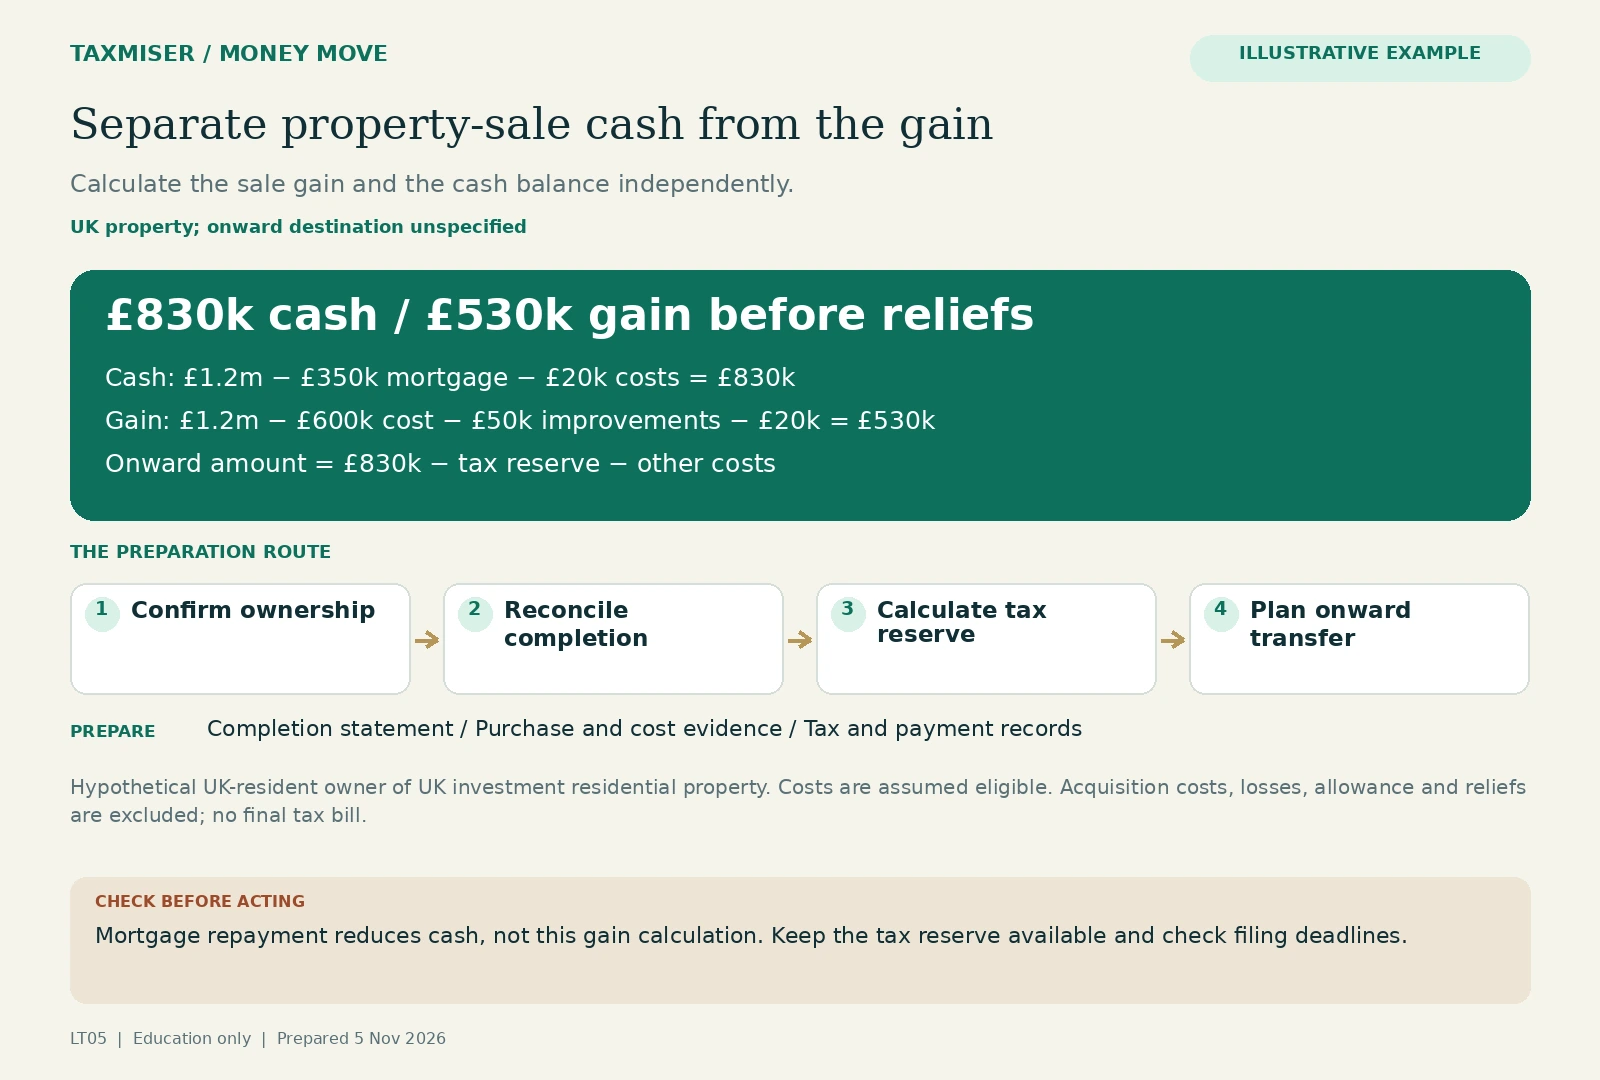 UK property; onward destination unspecified · Illustrative example
Separate property-sale cash from the gain
Calculate the sale gain and the cash balance independently.
£830k cash / £530k gain before reliefs
See the steps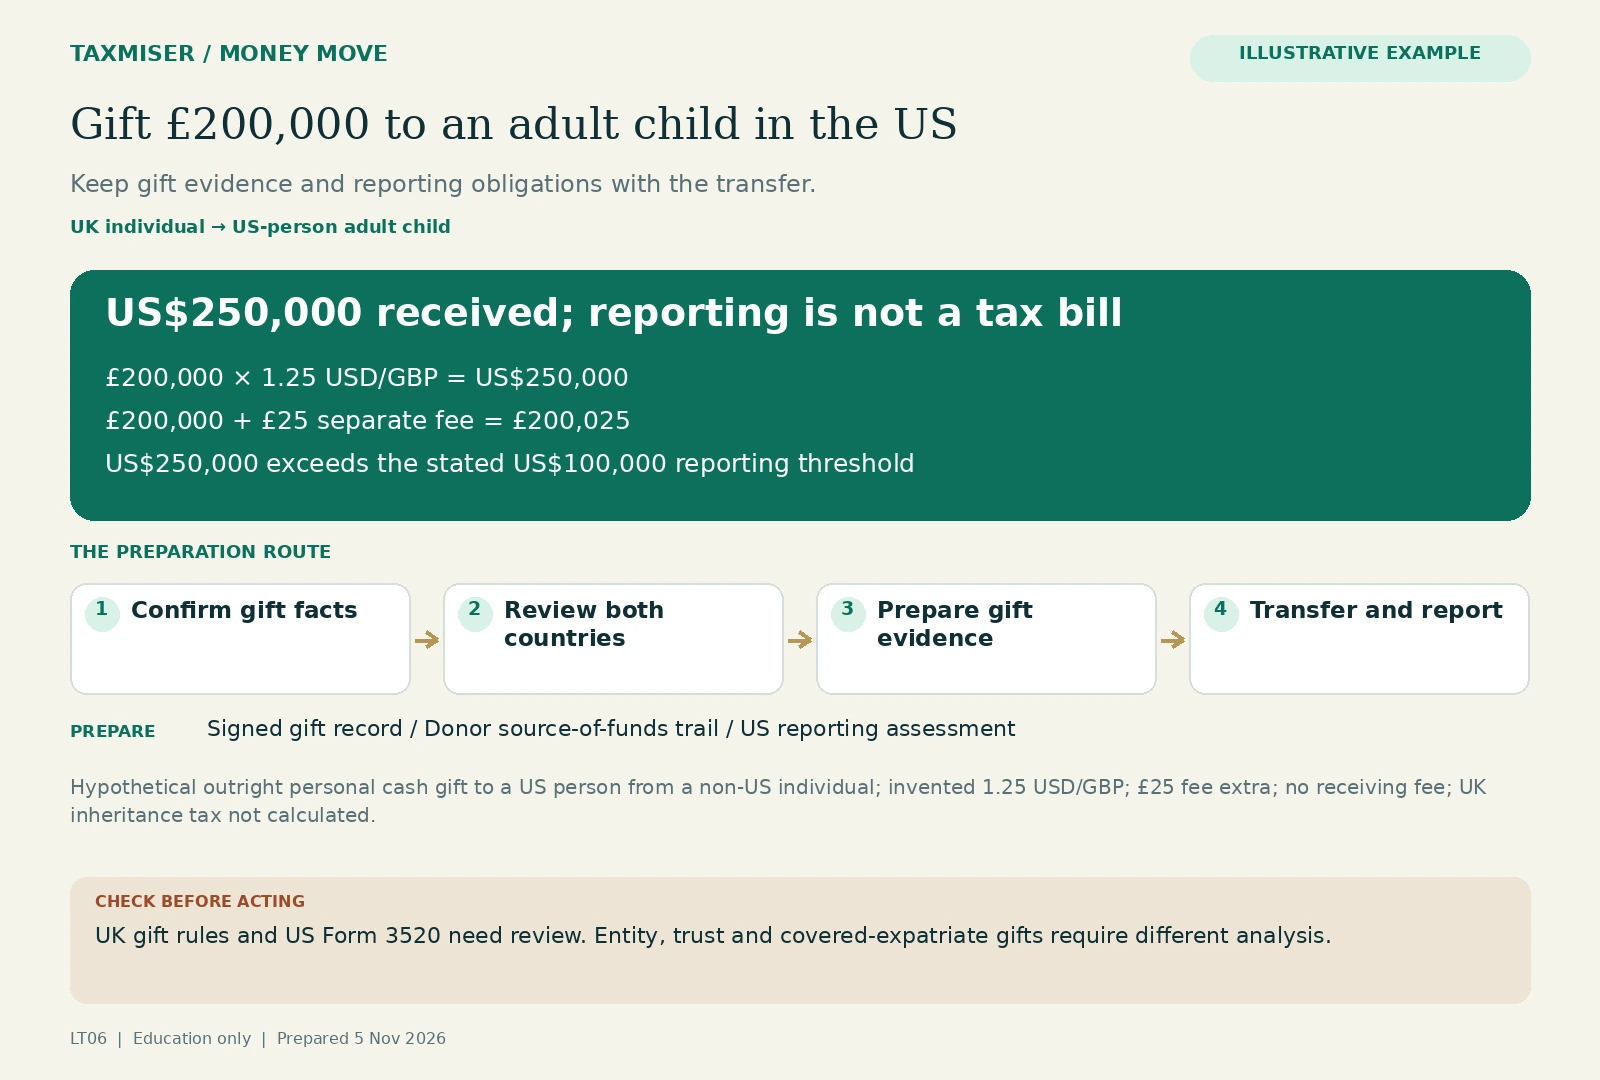 UK individual → US-person adult child · Illustrative example
Gift £200,000 to an adult child in the US
Keep gift evidence and reporting obligations with the transfer.
US$250,000 received; reporting is not a tax bill
See the steps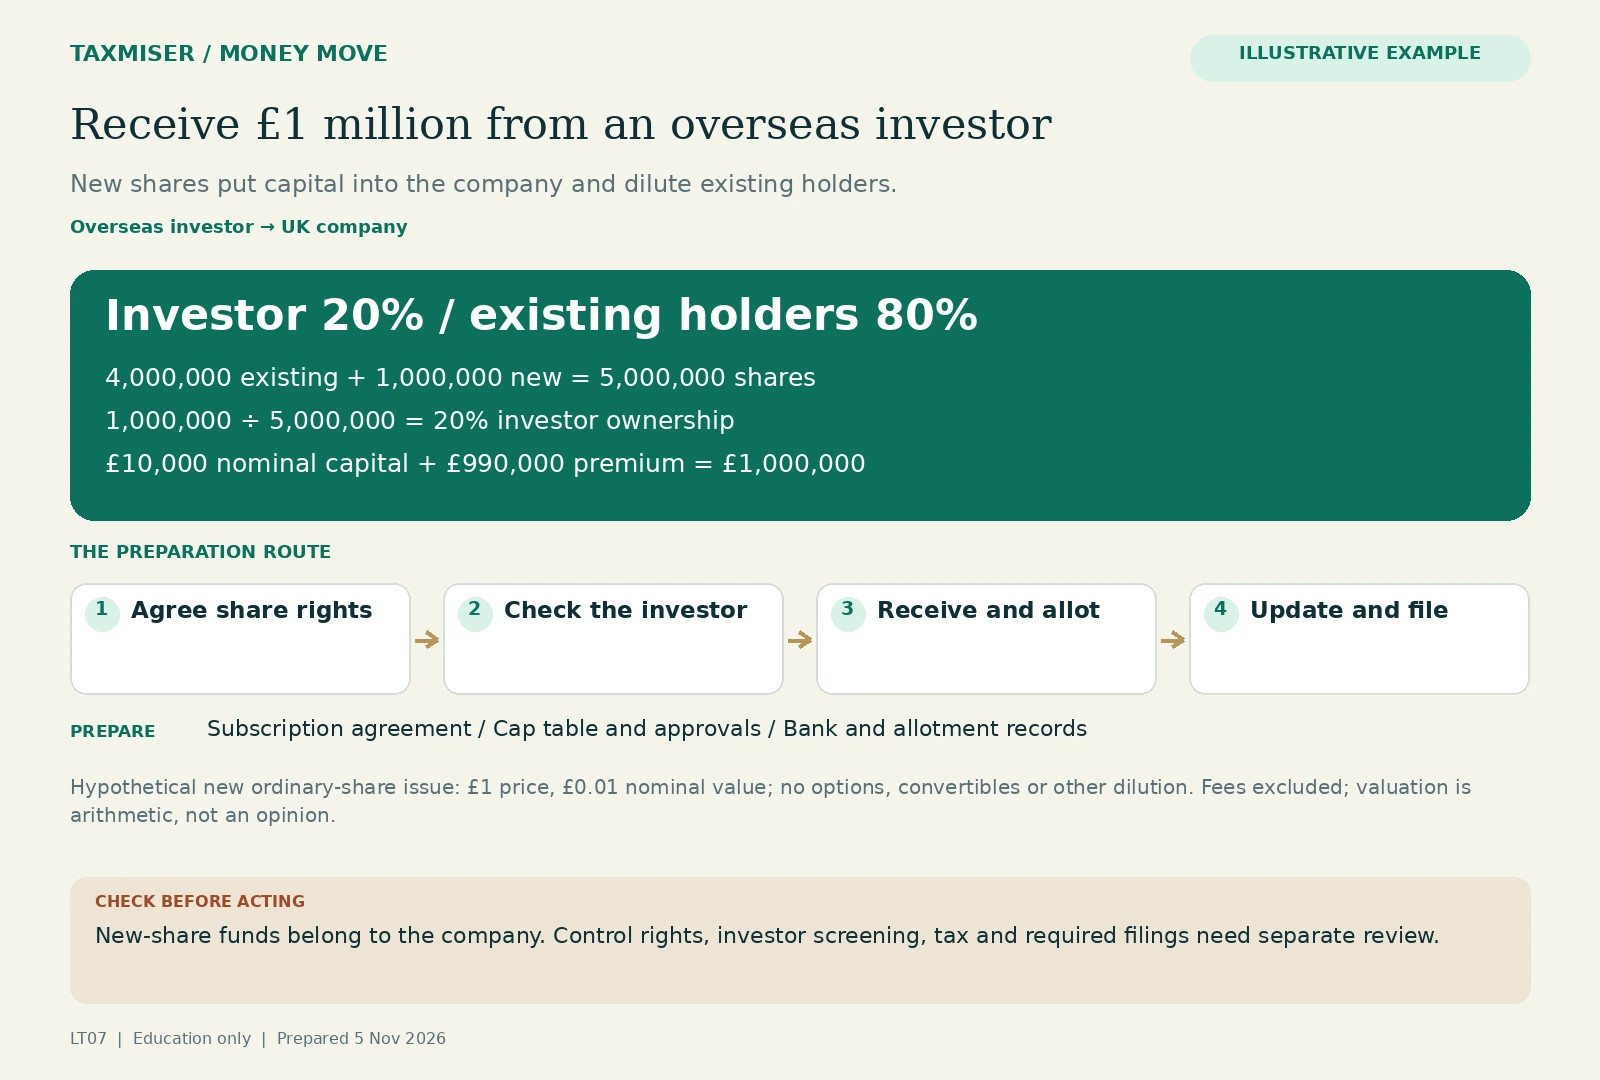 Overseas investor → UK company · Illustrative example
Receive £1 million from an overseas investor
New shares put capital into the company and dilute existing holders.
Investor 20% / existing holders 80%
See the steps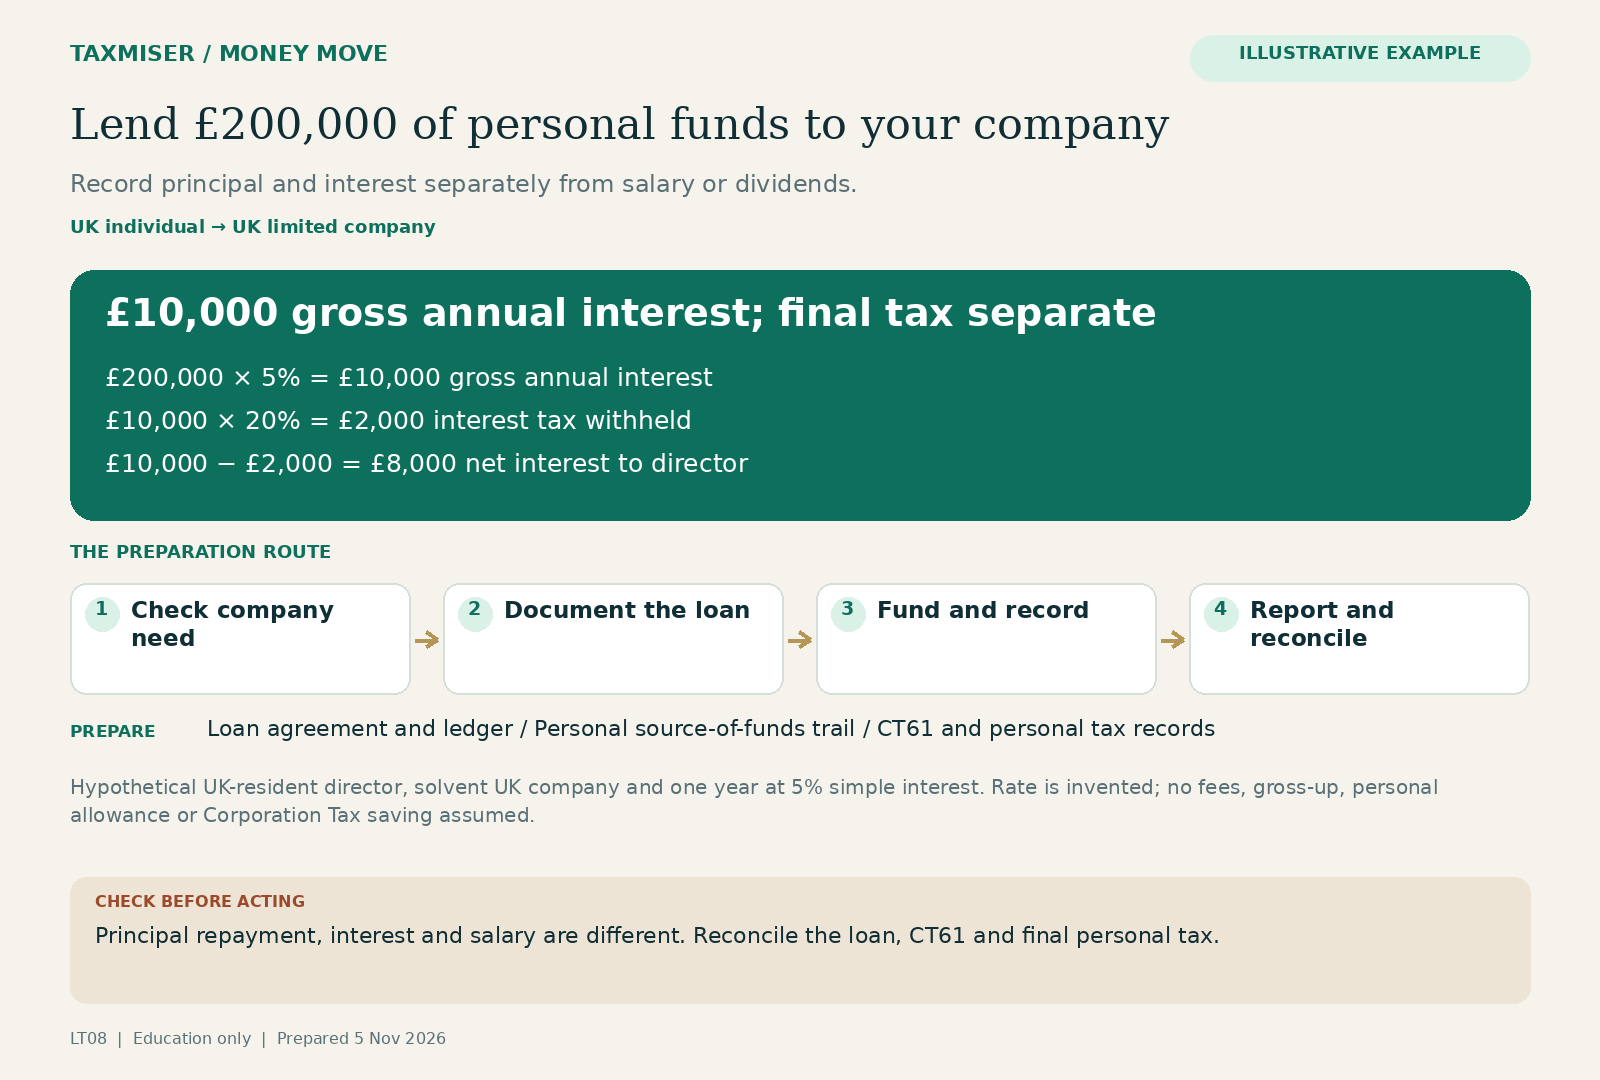 UK individual → UK limited company · Illustrative example
Lend £200,000 of personal funds to your company
Record principal and interest separately from salary or dividends.
£10,000 gross annual interest; final tax separate
See the steps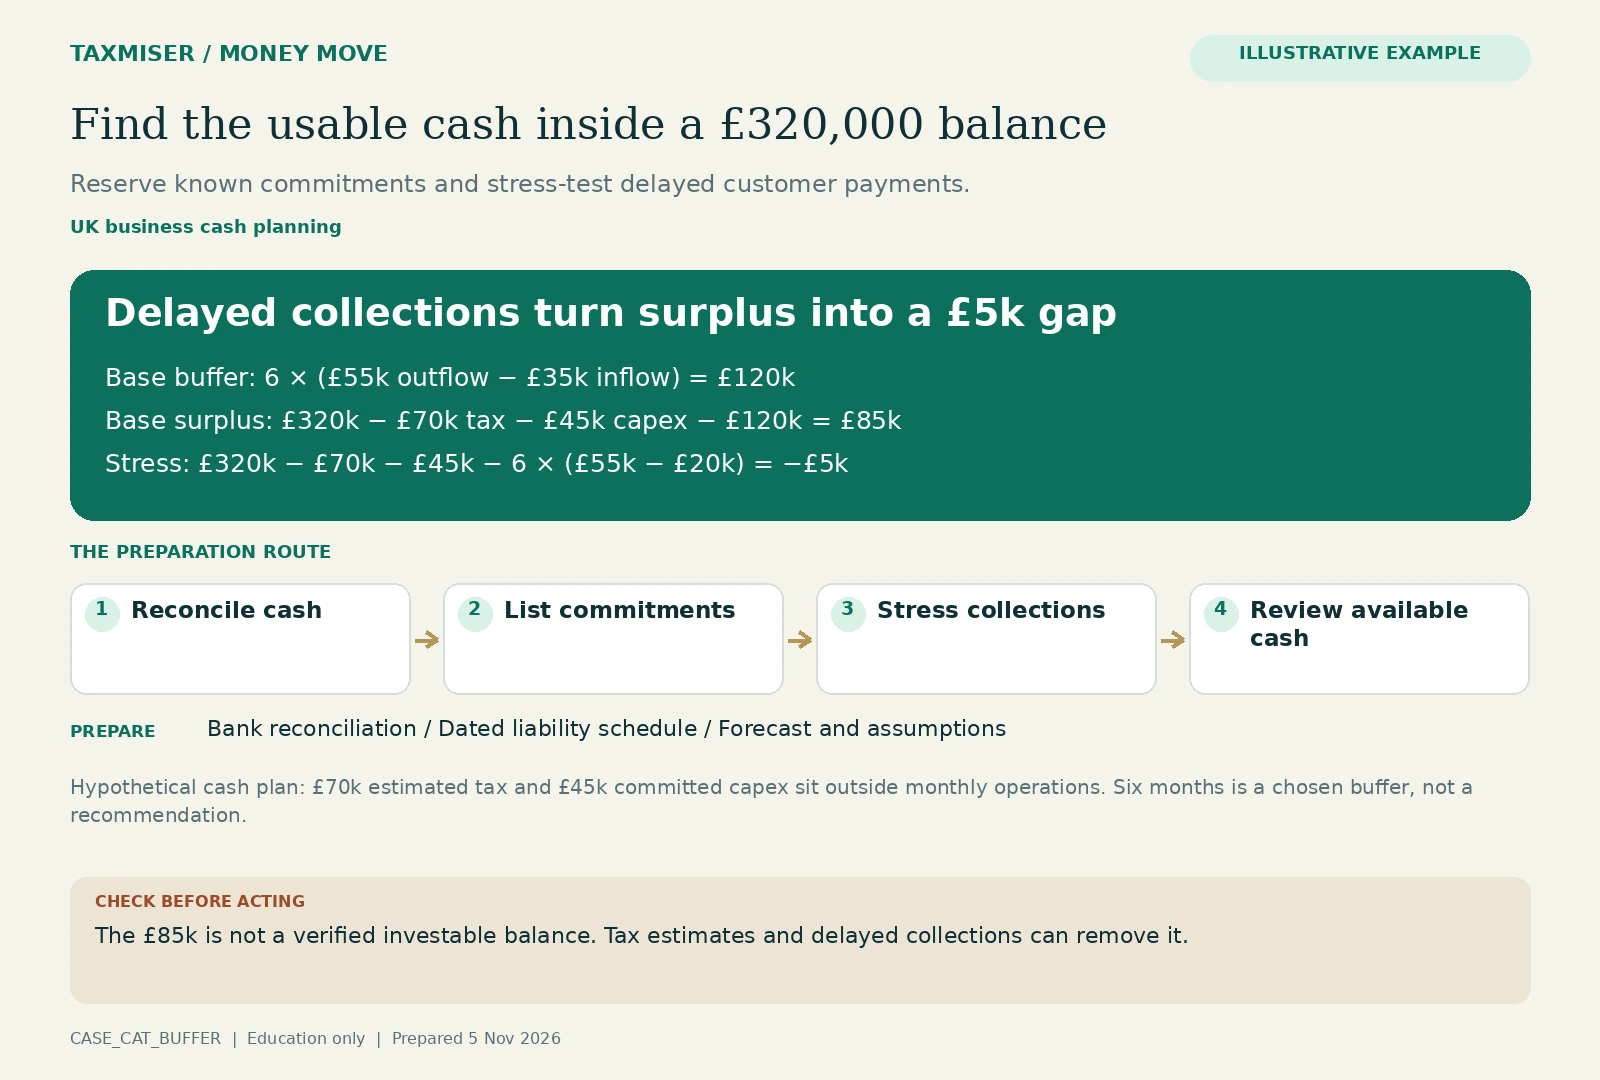 UK business cash planning · Illustrative example
Find the usable cash inside a £320,000 balance
Reserve known commitments and stress-test delayed customer payments.
Delayed collections turn surplus into a £5k gap
See the steps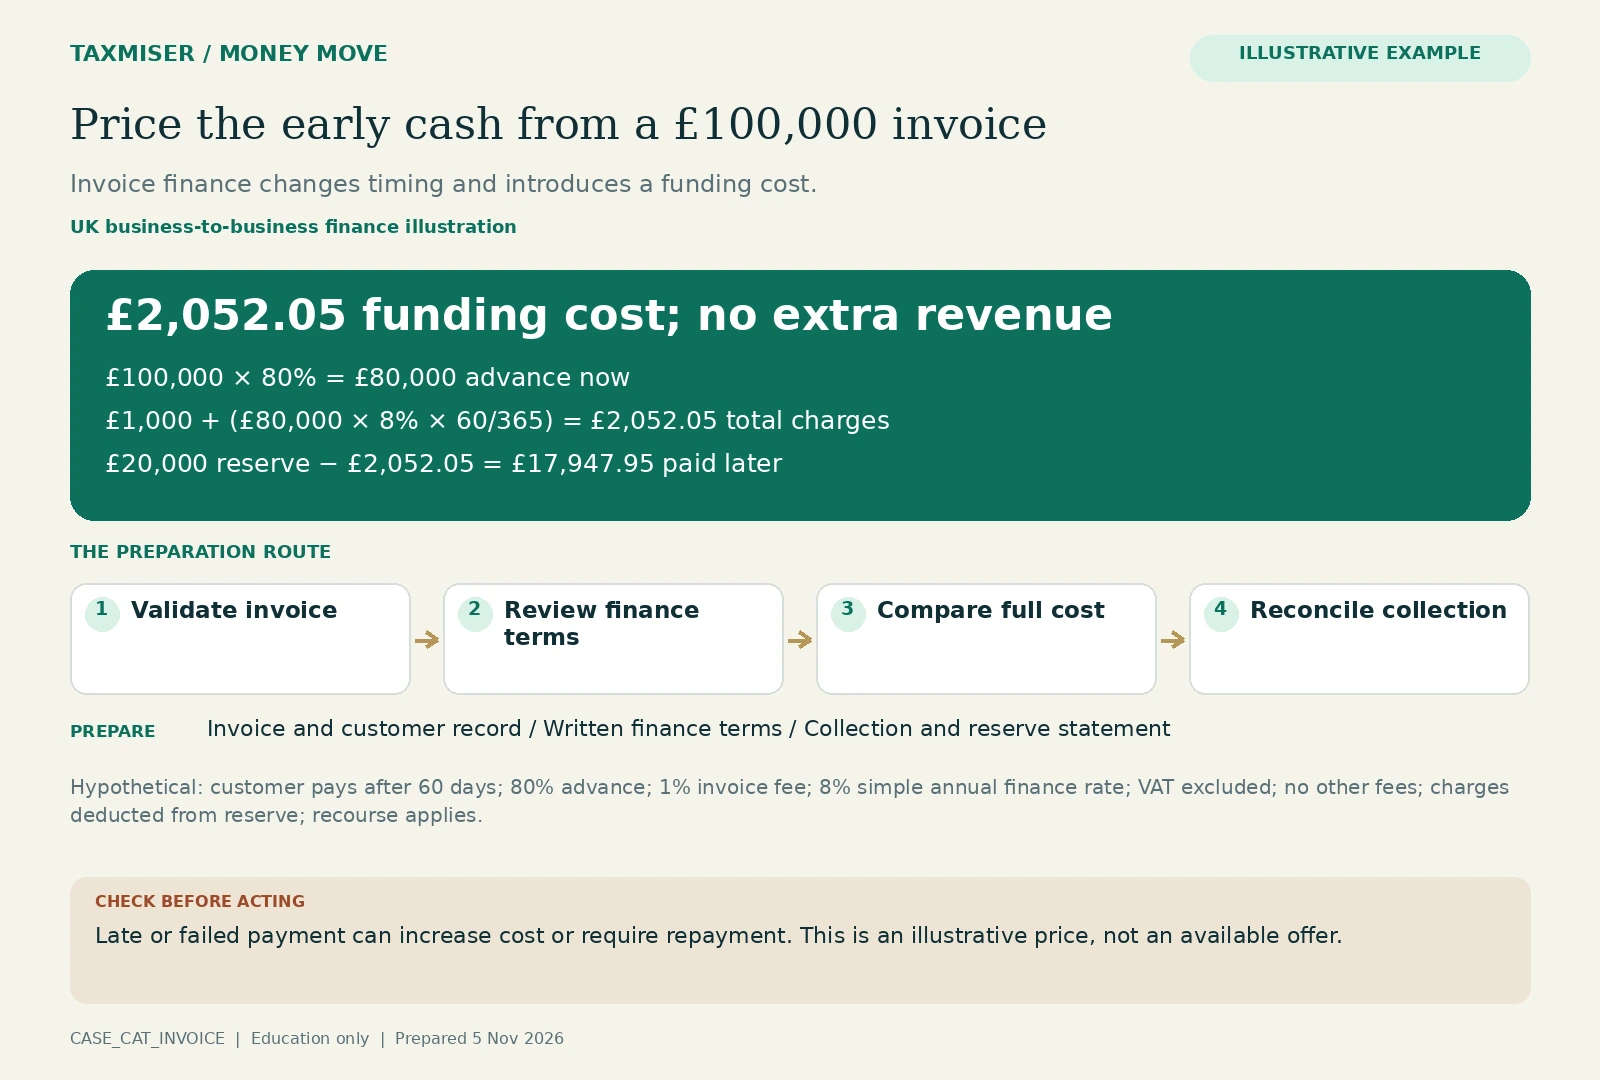 UK business-to-business finance illustration · Illustrative example
Price the early cash from a £100,000 invoice
Invoice finance changes timing and introduces a funding cost.
£2,052.05 funding cost; no extra revenue
See the steps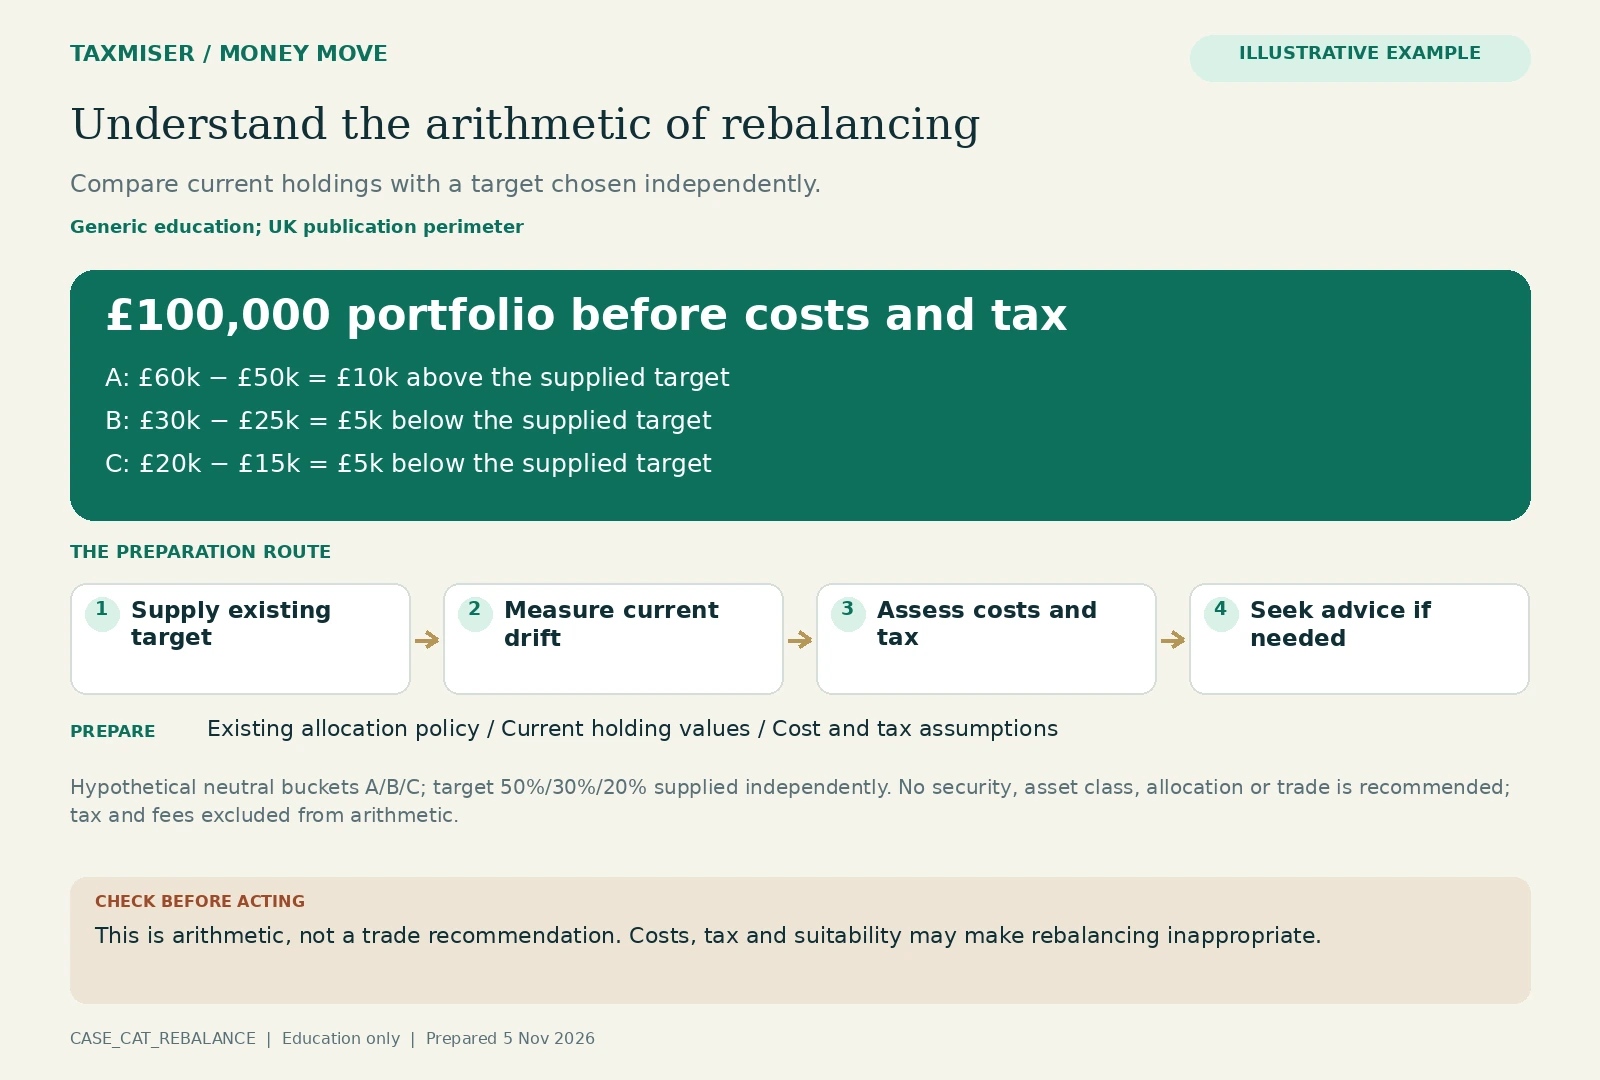 Generic education; UK publication perimeter · Illustrative example
Understand the arithmetic of rebalancing
Compare current holdings with a target chosen independently.
£100,000 portfolio before costs and tax
See the steps
Calculators
Put in your own numbers and see what you could save before you move any money.
Currency transfer cost
Compare how much actually arrives from two or three transfer quotes for the same amount sent.
Open calculatorPay a foreign invoice
Find how much you need to send so a fixed foreign-currency invoice is paid in full.
Open calculatorCash buffer and planning surplus
Separate tax, planned spending and a safety buffer from the cash you could plan with.
Open calculatorInvoice finance cost
See the advance, the fees and what comes back later when you finance an unpaid invoice.
Open calculatorTarget difference
Work out the gap between what you hold now and target amounts you have already chosen.
Open calculator
My cost tracker
Note each fee, cost or saving you find, so you can see the total you've kept.
Sign in as a member to save this to your account.
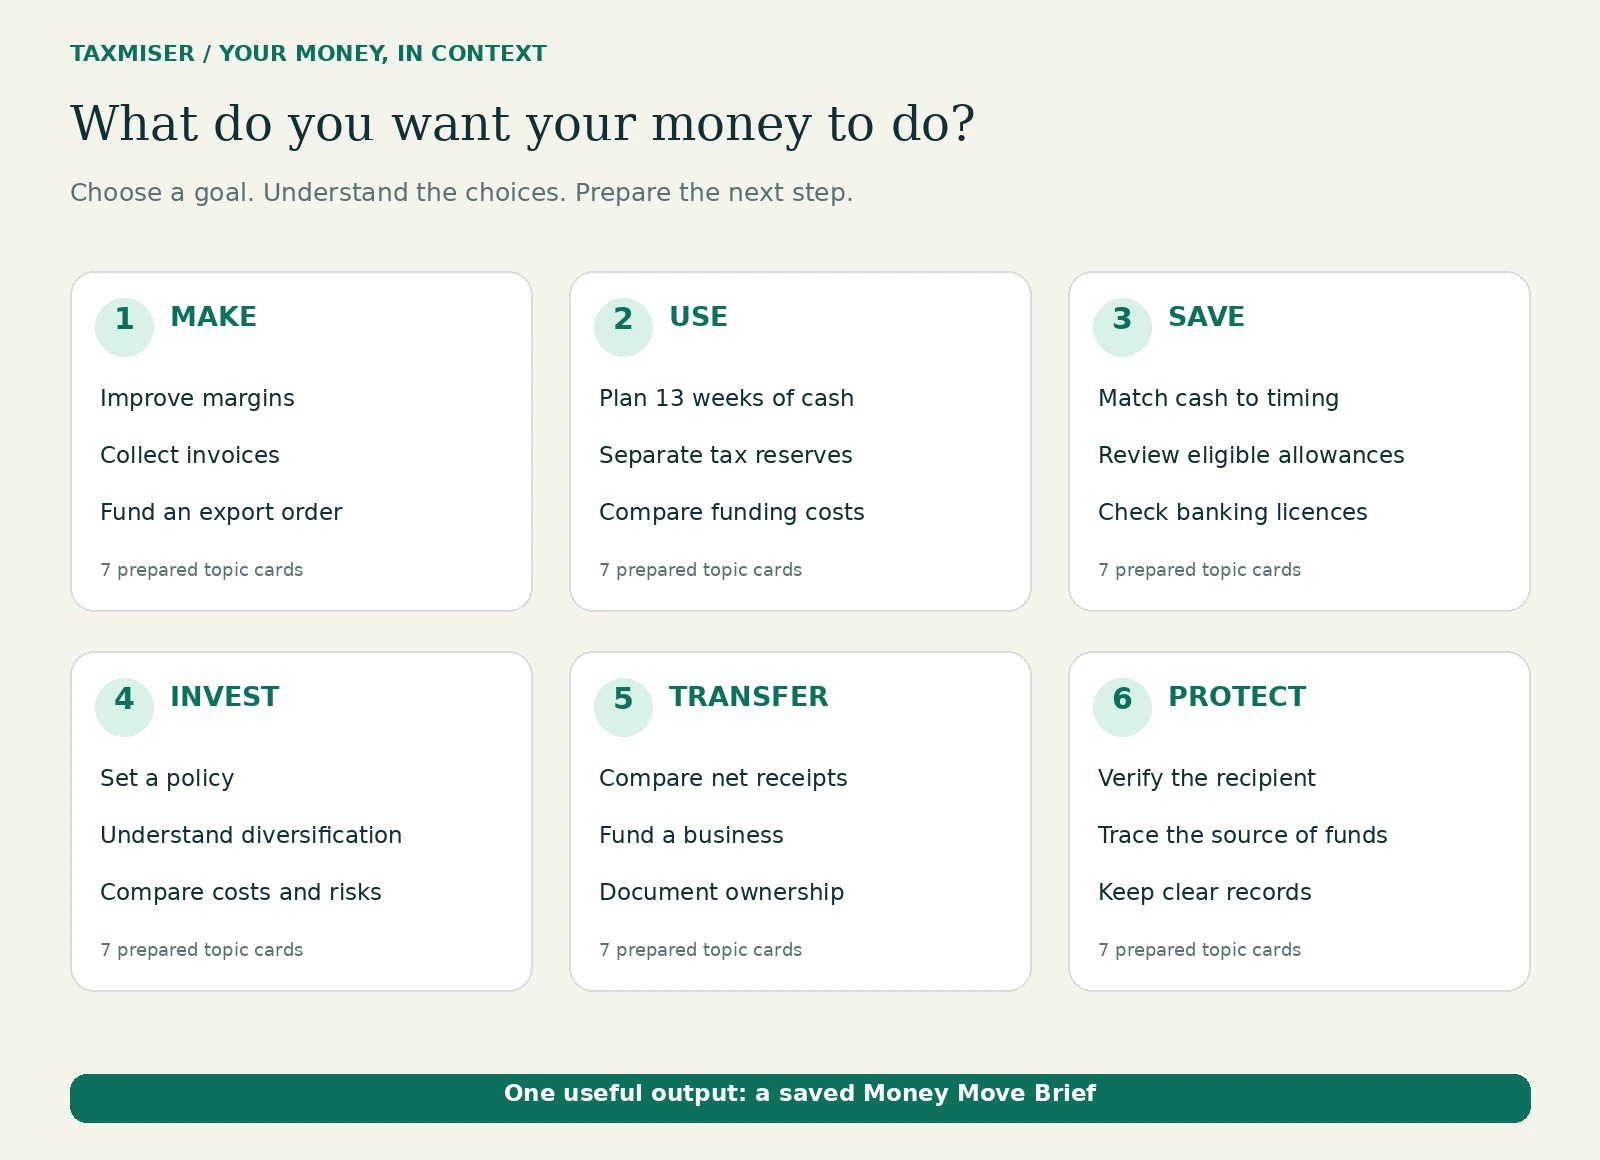
What do you want your money to do?
- make · beginner
Keep more of each sale
See where fees, direct costs and discounts reduce your margin.
Members get: A contribution-margin worksheet and break-even price comparison.
Illustrative unit economics; exclude VAT consistently and include refunds, fulfilment and variable costs. A higher price can reduce demand.
Official source - make · beginner
Invoice correctly the first time
Reduce avoidable invoice queries.
Members get: Invoice completeness checklist with purchase-order, supply-date and VAT fields.
Invoice and VAT rules depend on the entity and supply. A complete invoice does not guarantee collection.
Official source - make · intermediate
Use deposits and milestones
Match payment timing to project delivery.
Members get: Contract discussion prompts and milestone cash-flow model.
Customer terms, refund obligations and VAT tax points require review. Do not describe a deposit as earned profit automatically.
Official source - make · beginner
Recover overdue invoices
Build a documented reminder and escalation process.
Members get: Ageing dashboard, reminder templates and late-payment eligibility checklist.
Contractual and statutory rights differ; debt recovery can harm a relationship. Do not apply consumer rules to commercial debts.
Official source - make · intermediate
Turn unpaid invoices into working capital
Compare invoice finance with waiting for collection.
Members get: Advance, fee, financing-cost and recourse calculator.
Finance accelerates cash rather than creating profit. Check customer eligibility, disputed debts, recourse, security and all fees.
Official source - make · advanced
Fund an export order
Map the cash required before an overseas buyer pays.
Members get: Order-to-cash timeline, finance/insurance questions and UKEF eligibility links.
Cover and financing are conditional; currency, buyer, country and sanctions risks remain.
Official source - make · intermediate
Reinvest with a payback plan
Compare a growth project with preserving liquidity.
Members get: Incremental cash-flow, payback and downside worksheets.
Projected revenue is uncertain. Capital-allowance relief does not make unneeded spending profitable.
Official source - use · beginner
Build your 13-week cash plan
Spot a cash shortfall before it becomes urgent.
Members get: Weekly inflow/outflow schedule with base and delayed-payment scenarios.
Forecast dates and probabilities must be updated; profit is not cash.
Official source - use · beginner
Keep tax money available
Separate expected tax commitments from spendable cash.
Members get: Tax due-date calendar and reserve inputs reviewed by an accountant.
A planning reserve is not legally ring-fenced. Liability calculations depend on tax year, income, VAT and payroll.
Official source - use · advanced
Review salary, dividends and expenses
Understand the lawful routes for personal remuneration.
Members get: Scenario comparison showing company cost, personal receipts and missing inputs.
Dividends require available profits and paperwork; payroll and benefit rules apply. No universal optimum salary or guaranteed tax saving.
Official source - use · advanced
Consider an employer pension contribution
Compare retirement funding with taking cash now.
Members get: Contribution checklist and adviser handoff with annual-allowance questions.
Check remuneration justification, annual allowance, taper, money-purchase allowance and access restrictions. Tax treatment needs a current adviser review.
Official source - use · intermediate
Repay money you lent your company
Separate repayment of loan principal from remuneration.
Members get: Loan ledger reconciliation, original funding evidence and repayment record.
Confirm the debt is genuine and the company can pay; interest has separate tax/reporting treatment. Do not disguise earnings as loan repayment.
Official source - use · intermediate
Compare buying, leasing and financing
See total cash cost across the same period.
Members get: Deposit, instalment, interest, maintenance, residual-value and tax-assumption table.
Check ownership, early-exit charges, security, VAT and allowance eligibility. Lower monthly cost may mean higher total cost.
Official source - use · beginner
Compare debt repayment with saving
Check the cost of debt against the net return on cash.
Members get: After-fee comparison retaining an emergency buffer.
Priority debts and penalties matter. Company and personal debt decisions differ; retain required liquidity.
Official source - save · beginner
Set an emergency reserve
Plan for an interruption to income.
Members get: Essential-spending worksheet and user-chosen reserve scenarios.
The reserve size is a personal planning assumption; avoid promising a universal number. Accessibility and deposit eligibility matter.
Official source - save · beginner
Match cash to when you need it
Separate immediate bills, planned spending and longer-term money.
Members get: Time-bucket planner that shows withdrawal restrictions and liquidity gaps.
Time horizon alone does not establish investment suitability; cash can lose purchasing power.
Official source - save · beginner
Check your ISA allowance
Understand a tax wrapper before choosing an investment.
Members get: Tax-year allowance tracker and cash-versus-investment risk explanation.
ISA eligibility and subscription rules apply; an ISA is a wrapper, and investments inside it can fall. Current 2026/27 overall limit is £20,000; reverify at publication.
Official source - save · intermediate
Map bank protection by licence
See when different bank brands share a protection limit.
Members get: Bank-licence exposure map and official FSCS checker links.
As checked 5 Nov 2026, standard cover is £120,000 per eligible depositor per authorised firm. Shared licences aggregate. Business eligibility varies; safeguarding is different.
Official source - save · beginner
Compare savings after tax and fees
Compare the net amount retained over the same period.
Members get: Gross interest, fees, withdrawal rules and user-supplied tax scenario calculator.
Rates can change, fixed terms restrict access and personal allowances are not company allowances.
Official source - save · intermediate
Check VAT cash-accounting eligibility
Review whether VAT timing better follows customer receipts.
Members get: Eligibility checklist and timing comparison with normal accounting.
Input VAT recovery timing also changes. The scheme has exclusions and turnover tests; it is not a tax reduction.
Official source - save · intermediate
Plan qualifying business equipment
Check relief before buying equipment you actually need.
Members get: Asset-class checklist and cost-versus-tax-relief worksheet.
AIA/full-expensing eligibility and disposal charges differ. Relief reduces taxable profit, not necessarily tax pound for pound.
Official source - invest · intermediate
Write an investment policy
Record objectives, liquidity needs and permitted risks.
Members get: A blank policy template and questions for an authorised adviser.
Educational organisation only; no personalised security selection or buy/sell instruction.
Official source - invest · beginner
Understand diversification
See how concentration changes exposure to a loss.
Members get: Interactive educational portfolio buckets without recommended allocations.
Diversification does not eliminate market loss. Correlations and liquidity can change.
Official source - invest · beginner
Measure investment fee drag
See how recurring costs affect an illustrative outcome.
Members get: User-entered platform, fund, dealing and FX fee calculator.
Assumed returns are not forecasts; include tax and investment risk separately. No provider ranking based on undisclosed commissions.
Official source - invest · intermediate
Understand portfolio rebalancing
See the arithmetic of returning to a chosen mix.
Members get: Drift diagram and educational before/after calculator.
User-defined targets are not endorsed allocations. Sales can incur tax, costs and market risk; no trade execution.
Official source - invest · advanced
Review pension limits before funding
Identify the facts an adviser needs before a large contribution.
Members get: Annual-allowance, relevant-earnings and prior-contribution checklist.
Employer and personal contribution relief differ. Taper, carry forward and access rules need fact-specific review.
Official source - invest · advanced
Evaluate a holding-company structure
See ownership, cash flow and commercial purpose together.
Members get: Entity map plus formation, distributions, financing and adviser-cost checklist.
A holding company does not automatically remove tax, protect against every creditor or justify artificial charges. Obtain legal and multi-jurisdiction tax advice.
Official source - invest · advanced
Compare expansion with acquisition
Assess purchase price, funding and integration cash needs.
Members get: Due-diligence question pack and downside cash model.
Asset/share purchases, liabilities and taxes differ. No assurance that an acquisition generates value.
Official source - transfer · beginner
Compare the amount that arrives
See the effect of both exchange rate and fees.
Members get: Same-time, same-budget comparison including sender, intermediary and recipient charges.
Quotes, limits and settlement times change; fees may be unknown until confirmed. The cheapest quote may have different protection.
Official source - transfer · intermediate
Pay an overseas supplier
Connect the invoice, beneficiary and payment purpose.
Members get: Document checklist, approval steps and payment-reference template.
Verify goods/services, sanctions, duties, VAT and account changes. A transfer confirmation is not delivery proof.
Official source - transfer · intermediate
Move savings between your accounts
Prepare a traceable transfer of your own money.
Members get: Ownership, source-of-funds, destination and tax-residence checklist.
The transfer method does not settle the underlying tax position; historic foreign income and residence rules need review.
Official source - transfer · advanced
Document an intercompany loan
Classify funding as an actual loan with repayment terms.
Members get: Loan purpose, rate, currency, tenor, approval and related-party evidence pack.
Transfer pricing, interest deductibility, withholding, thin-capitalisation and local rules can apply; SME exemptions are not universal.
Official source - transfer · advanced
Fund an overseas subsidiary with equity
Understand how equity funding differs from a loan.
Members get: Board-resolution, subscription, ownership and destination-reporting checklist.
Legal form, local registration and tax treatment require both-country advice. A personal transfer is not automatically company capital.
Official source - transfer · advanced
Make a documented family gift
Record that money is an outright gift and why.
Members get: Gift-letter checklist, donor records and cross-border questions.
UK inheritance-tax, retained benefit, residence and destination reporting rules may apply. Do not promise gifts are universally tax-free.
Official source - transfer · advanced
Check residence before moving funds
Ask the right tax questions before transferring historic overseas funds.
Members get: Residence timeline and source/year classification worksheet.
The four-year FIG regime replaced the remittance basis on 6 April 2025 but historic remittance-basis funds can remain relevant. Local and UK specialist advice is needed.
Official source - protect · beginner
Verify the recipient before paying
Reduce the risk of an unauthorised destination change.
Members get: Independent callback, payee-detail and dual-approval checklist.
Known contact channels must be verified independently; small test payments do not prove a transaction is legitimate. Never split payments to evade checks.
Official source - protect · beginner
Check the provider and permissions
Find the operating legal entity and verify its permissions.
Members get: Official FCA checker links and clone-firm warning prompts.
Authorisation does not mean every service is covered or every loss protected. Use official register contact details.
Official source - protect · intermediate
Build a source-of-funds pack
Make the transaction story easy to evidence.
Members get: Checklist linking bank statements, contract, sale, loan or inheritance to payment purpose.
Banks and providers determine required checks. The pack is not an AML certificate or guarantee of acceptance; do not upload unnecessary identity documents.
Official source - protect · beginner
Keep company and personal money distinct
Show who owns each account and each obligation.
Members get: Entity/account map and transaction classification checklist.
Separate legal entities require accurate records. Moving money between accounts does not itself make it a business expense.
Official source - protect · intermediate
Know when to use a professional
Identify which decision requires tax, legal or regulated investment expertise.
Members get: Handoff brief with relevant facts, questions and source links.
A membership disclaimer does not remove regulatory obligations. Tax advice, promotions, investment recommendations and payments have distinct boundaries.
Official source - protect · intermediate
Keep a minimal evidence vault
Organise useful documents with controlled access.
Members get: Document index, expiry/retention settings, redaction and export tools.
Collect only necessary personal data. Define purpose, lawful basis, retention, deletion and access logs before uploads launch.
Official source - protect · intermediate
Plan for a payment disruption
Prepare alternative access and authorisation for essential payments.
Members get: Payment calendar, approval coverage and contingency checklist.
Alternative banking must still pass normal identity and transaction checks. Do not treat backup accounts as a way around sanctions or controls.
Official source
These are educational examples, not customer results, tax rulings or advice. Your facts and each country's rules matter.