UK individual → US-person adult child · Illustrative example
Gift £200,000 to an adult child in the US
Keep gift evidence and reporting obligations with the transfer.
Money in
Donor pays: £200,025 including fee
Money out
Adult child receives: US$250,000
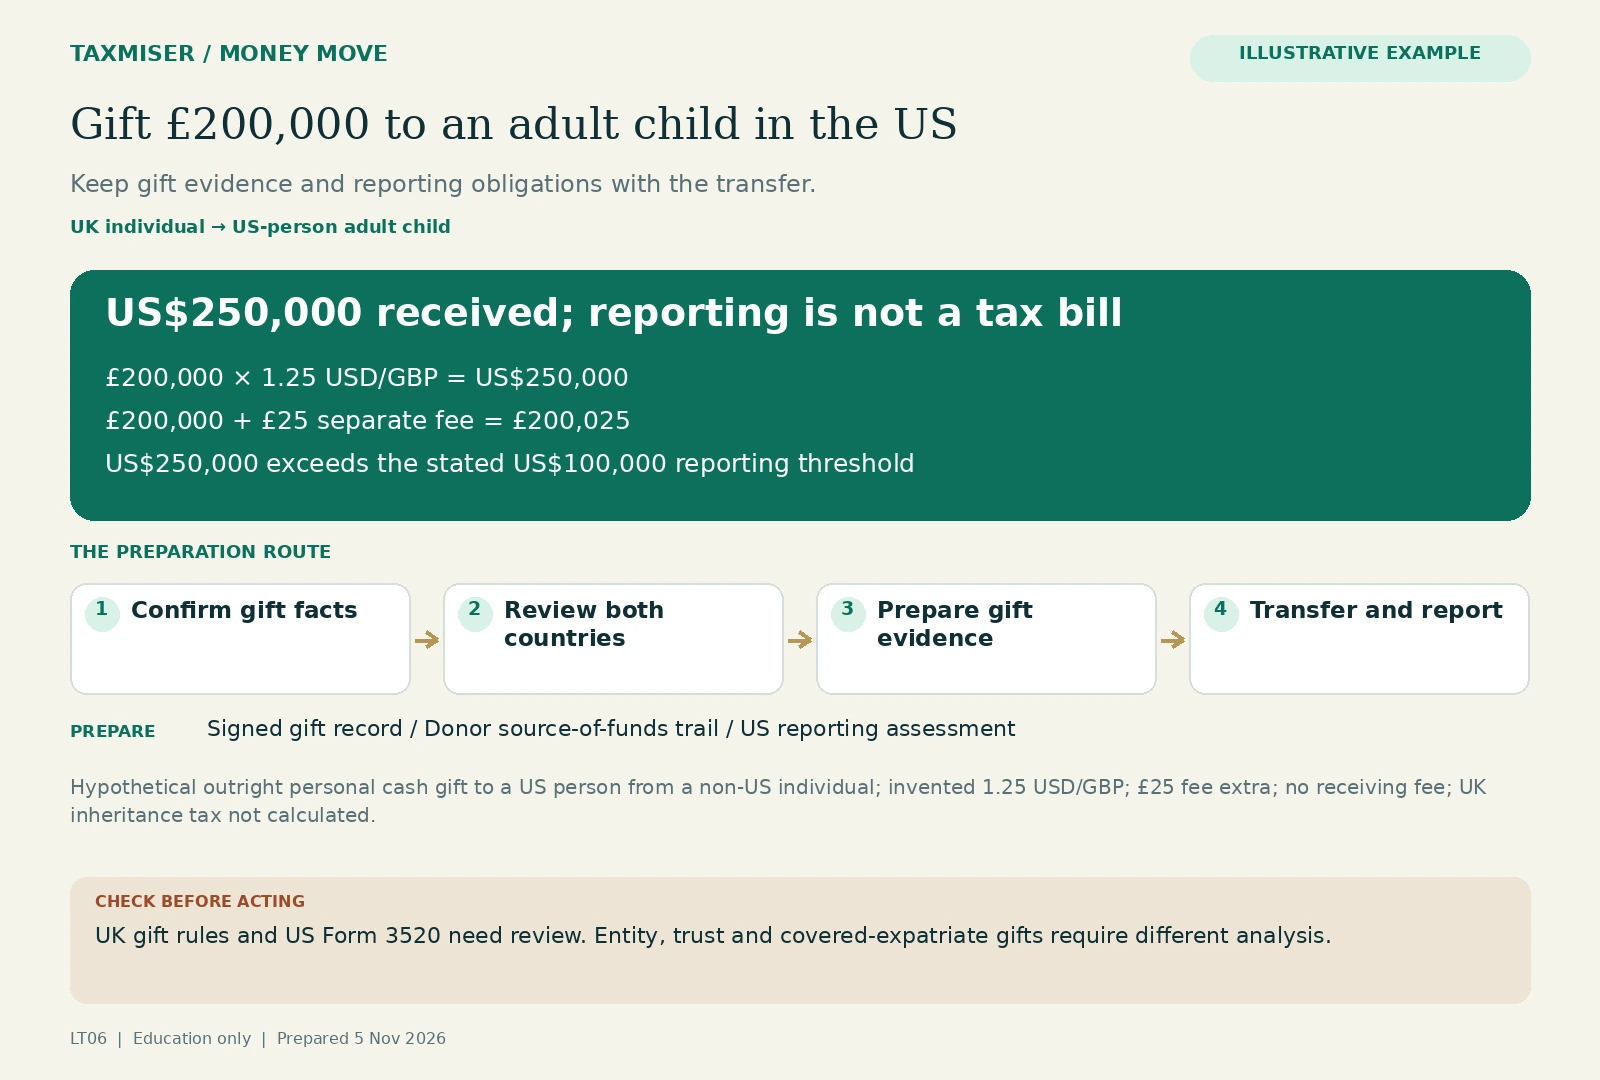
US$250,000 received; reporting is not a tax bill
- £200,000 × 1.25 USD/GBP = US$250,000
- £200,000 + £25 separate fee = £200,025
- US$250,000 exceeds the stated US$100,000 reporting threshold
Hypothetical outright personal cash gift to a US person from a non-US individual; invented 1.25 USD/GBP; £25 fee extra; no receiving fee; UK inheritance tax not calculated.
UK gift rules and US Form 3520 need review. Entity, trust and covered-expatriate gifts require different analysis.
Step by step
1. Confirm it is a gift
Record the donor and recipient identities, relationship, residence and genuine intention; distinguish a gift from a loan, salary or business distribution.
2. Review estate consequences
Ask a UK adviser about previous gifts, exemptions, the seven-year rule, retained benefits and any cross-border scope issues.
3. Review the US recipient position
Ask the US adviser about Form 3520, donor aggregation, trust/entity exceptions and the appropriate deadline.
4. Prepare bank evidence
Use a signed gift record, donor source-of-funds evidence and recipient account ownership confirmation.
5. Transfer with a truthful reference
Use verified account details and retain the exact FX/fee confirmation; do not divide gifts to disguise their nature or avoid reporting.
6. Keep both records
The donor retains the estate-planning history and the recipient retains evidence and any required information return.
Assumptions
- The donor is a UK-resident individual within the relevant UK inheritance-tax analysis, and is not a US citizen, resident or covered expatriate.
- The adult recipient is a US person. The cash is an outright personal gift, with no services, repayment requirement, trust, company payer or retained benefit.
- The donor gives £200,000; an invented rate of 1.25 USD/GBP delivers $250,000. A £25 fee is paid separately.
- No UK annual exemption, normal-expenditure exemption, prior gifts, nil-rate-band calculation or final inheritance-tax liability is assumed.
- No other gifts from related donors are assumed for the arithmetic; actual US reporting must consider aggregation.
Documents to gather
- Signed gift letter/deed as advised
- Donor identity, source-of-funds and prior-gift history
- Recipient identity and account evidence
- Transfer confirmation and receiving statement
- UK adviser notes
- US Form 3520 assessment and filing evidence if required
Tax and reporting questions
- Outright gifts can be potentially exempt for UK inheritance-tax purposes; survival for seven years, available exemptions, prior gifts and retained benefits matter. Seven years is not a universal exemption for every arrangement.
- For the stated US-person recipient and nonresident-individual donor facts, gifts exceeding $100,000 in aggregate generally require Form 3520 reporting. Related donors are aggregated, and entity/trust gifts have different rules.
- The IRS generally distinguishes a qualifying foreign gift from gross income. An information-return obligation does not itself establish that the cash gift is taxable income, and exceptions still require review.
Risks
- Gift actually functioning as remuneration or a loan
- Omitted US information return
- UK donor death within seven years
- Retained benefit or trust complications
- Sending company money as if it were a personal gift
Things we cannot know for you
- Donor’s full UK IHT status/history and previous gifts
- Recipient US status and filing circumstances
- Any state or other-country rules
- Gift-document requirements imposed by the receiving institution
When to bring in a professional
- Every substantial cross-border gift
- Trusts, entities or covered-expatriate connections
- Donor or recipient with dual residence/citizenship
- Donor retaining use/control
- A gift that would impair the donor’s financial security
Educational example. Figures are assumptions, not a quote, tax ruling or guaranteed saving. Your facts and both countries’ rules matter.
My brief
Write down how this applies to you. It saves to your account as you type.
Sign in as a member to save this to your account.
Sources
- Using payment service providers, Financial Conduct Authority (checked 2026-11-05)
- AMLG11630: Source of Funds & Source of Wealth, HMRC (checked 2026-11-05)
- Inheritance Tax: Rules on giving gifts, HMRC (checked 2026-11-05)
- Gifts from foreign person, US Internal Revenue Service (checked 2026-11-05)