UK → US · Illustrative example
Move £500,000 between your UK and US accounts
Compare transfer proceeds after fees; source tax is a separate question.
Money in
Total sender budget: £500,000
Money out
Quote B receipt: US$623,718.81
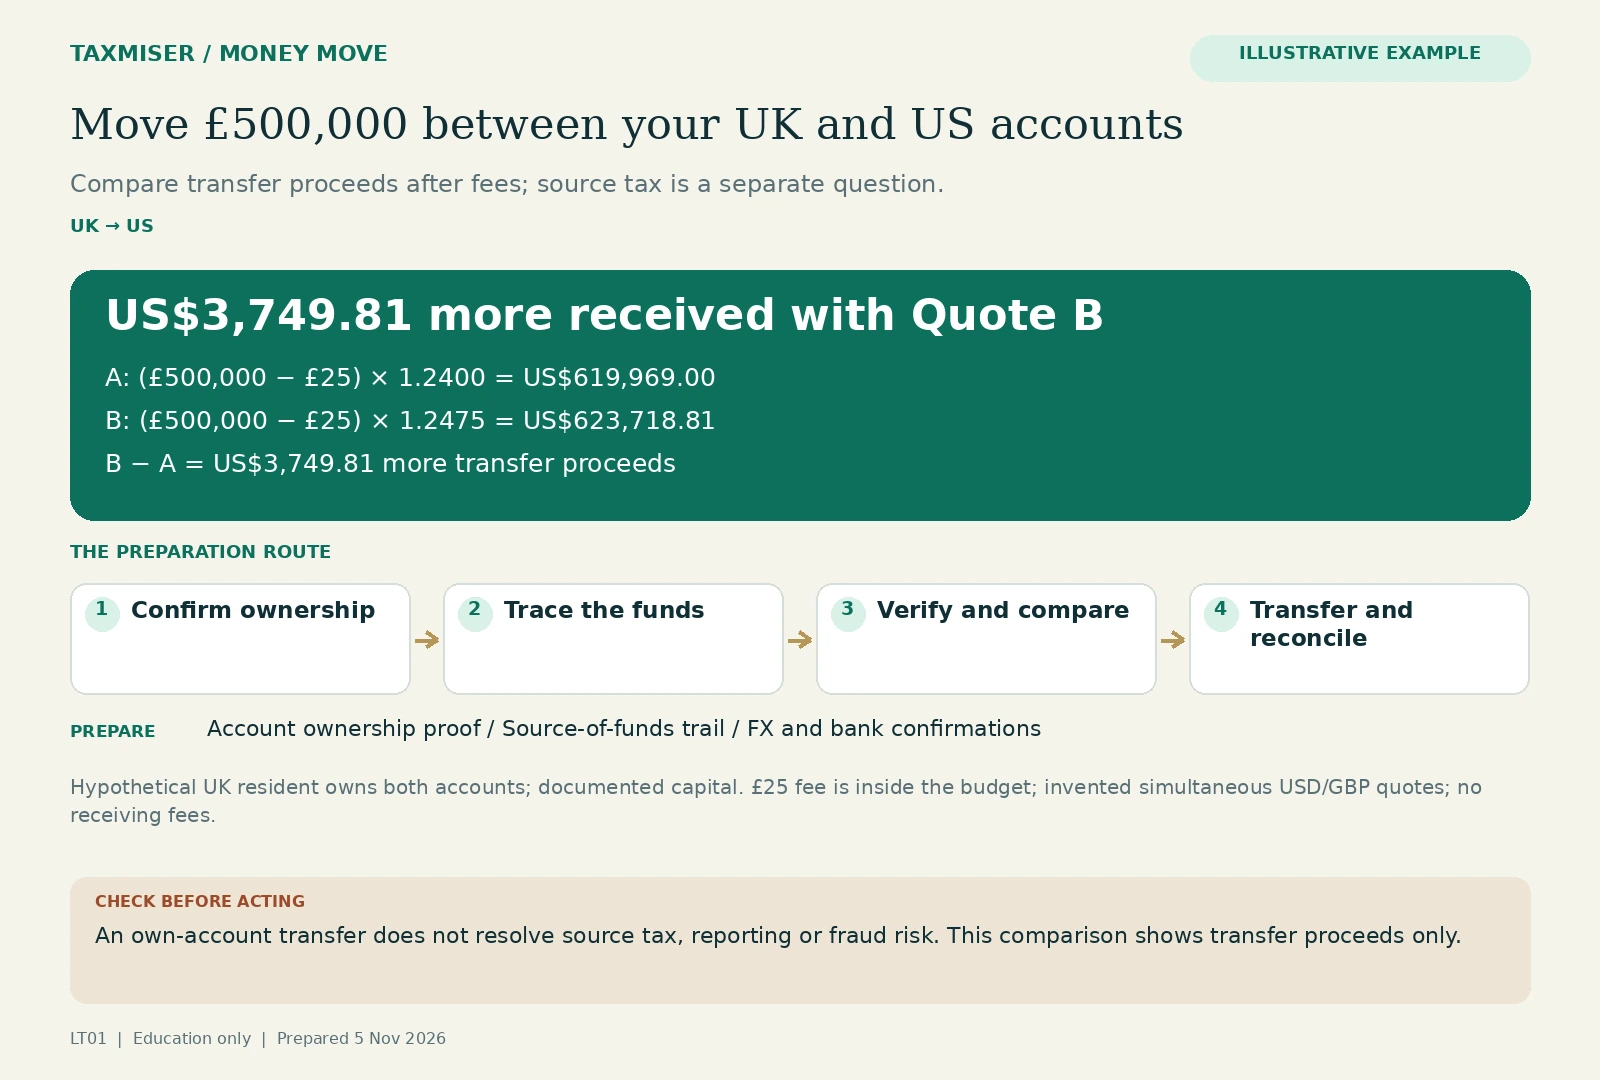
US$3,749.81 more received with Quote B
- A: (£500,000 − £25) × 1.2400 = US$619,969.00
- B: (£500,000 − £25) × 1.2475 = US$623,718.81
- B − A = US$3,749.81 more transfer proceeds
Hypothetical UK resident owns both accounts; documented capital. £25 fee is inside the budget; invented simultaneous USD/GBP quotes; no receiving fees.
An own-account transfer does not resolve source tax, reporting or fraud risk. This comparison shows transfer proceeds only.
Step by step
1. Confirm ownership and purpose
Record both account holders and the genuine purpose. Ask both banks about large-transfer procedures before agreeing a purchase deadline.
2. Explain the origin
Build a trail from the income, sale, inheritance or other event that created the capital to the current account. A recent bank balance alone may be insufficient.
3. Check the provider
Verify the actual legal entity, relevant permissions and official contact details; understand bank-deposit protection versus safeguarding.
4. Compare the final result
Request simultaneous written quotes showing the exact amount debited, the minimum/expected amount received, all fees and settlement assumptions.
5. Verify destination and execute
Independently verify account details through a known channel. Agree any test payment or operational instalments with the provider for genuine operational reasons, never to avoid checks.
6. Reconcile and retain
Match the debit, FX confirmation and receiving-bank credit, then retain the source-of-funds and tax analysis.
Assumptions
- The sender is UK tax resident, is not a US citizen or US tax resident, and legally owns both accepted bank accounts.
- The £500,000 is documented capital with the tax treatment of its origin already established. There is no gift, business payment or beneficial-owner change.
- The total sending budget is £500,000 including a £25 sending fee. No intermediary or receiving fee applies in this simplified illustration.
- The reference rate is an invented 1.2500 USD per GBP, not a current market rate. Quote A is 1.2400 and Quote B is 1.2475 USD per GBP, captured at the same illustrative moment.
- Provider availability, bank acceptance, limits, settlement time, final FX quote and any local reporting remain to be confirmed.
Documents to gather
- Identity/address evidence requested by the provider
- Proof of ownership of both accounts
- Historic statements tracing the funds
- Relevant payslips, tax returns, sale contract or estate documents
- FX quotes and fee disclosures
- Transfer confirmation and receiving statement
Tax and reporting questions
- Assess the tax treatment of the source and the person’s tax residence separately from the transfer. UK residents normally pay UK tax on foreign income; the FIG regime has eligibility and claim conditions.
- If the route is reversed into the UK, former remittance-basis users may still have a UK tax charge on untaxed pre-6 April 2025 foreign income or gains. Do not label all inbound capital tax-free.
- A US citizen/resident or other US person needs a separate foreign-account reporting review; FBAR is based on foreign-account interests and aggregate balances, not simply the size of one wire.
Risks
- FX movement while comparing quotes
- Intermediary charges or a rejected/returned payment
- Impersonation and changed beneficiary details
- Temporary holds while documents are checked
- Incorrectly treating untaxed income as clean capital
Things we cannot know for you
- Specific sender/receiver residence and US-person status
- Underlying capital history
- Provider permissions, protections, final quotes and delivery conditions
When to bring in a professional
- Any US citizenship, green card or tax residence
- Former UK remittance-basis use
- Funds mixed across years or sources
- Trust, cryptoasset or complex-company proceeds
- An overseas property purchase with a fixed completion date
Educational example. Figures are assumptions, not a quote, tax ruling or guaranteed saving. Your facts and both countries’ rules matter.
My brief
Write down how this applies to you. It saves to your account as you type.
Sign in as a member to save this to your account.
Sources
- Tax on foreign income, HMRC (checked 2026-11-05)
- Check if you can claim the 4-year foreign income and gains regime, HMRC (checked 2026-11-05)
- HS264: Remittance of pre-6 April 2025 foreign income and gains, and the temporary repatriation facility, HMRC (checked 2026-11-05)
- Using payment service providers, Financial Conduct Authority (checked 2026-11-05)
- AMLG11630: Source of Funds & Source of Wealth, HMRC (checked 2026-11-05)
- How to check a firm or individual is authorised, Financial Conduct Authority (checked 2026-11-05)
- Report of Foreign Bank and Financial Accounts (FBAR), US Internal Revenue Service (checked 2026-11-05)
- Safeguarding requirements for payment and electronic money institutions, Financial Conduct Authority (checked 2026-11-05)