UK → China; USD settlement · Illustrative example
Pay a US$240,000 overseas supplier invoice
Compare the cash required for the same net invoice payment.
Money in
UK company pays: £192,409.77 with Quote B
Money out
Supplier receives: US$240,000
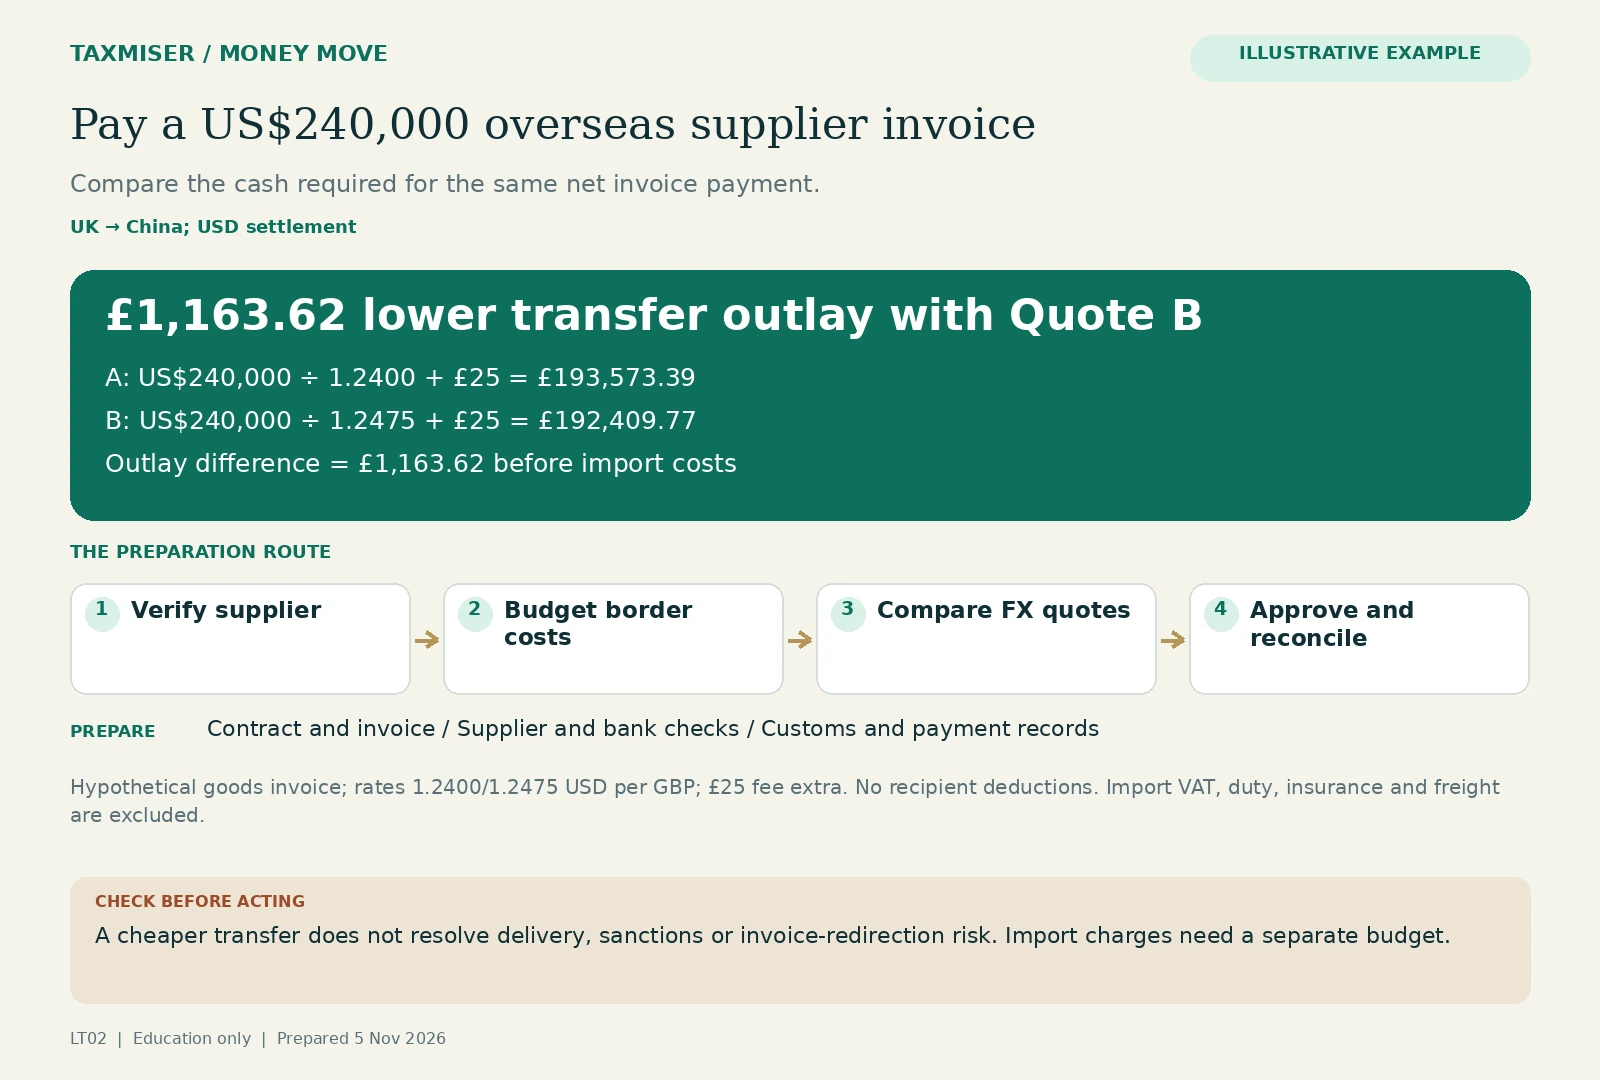
£1,163.62 lower transfer outlay with Quote B
- A: US$240,000 ÷ 1.2400 + £25 = £193,573.39
- B: US$240,000 ÷ 1.2475 + £25 = £192,409.77
- Outlay difference = £1,163.62 before import costs
Hypothetical goods invoice; rates 1.2400/1.2475 USD per GBP; £25 fee extra. No recipient deductions. Import VAT, duty, insurance and freight are excluded.
A cheaper transfer does not resolve delivery, sanctions or invoice-redirection risk. Import charges need a separate budget.
Step by step
1. Validate the supplier and goods
Verify the registered supplier, beneficial ownership and product specifications; match the contract, purchase order and invoice.
2. Set payment protections
Agree currency, delivery terms, inspection milestones and responsibility for charges. Consider appropriate trade-finance or escrow services with qualified providers when the risk warrants it.
3. Plan the border costs
Confirm EORI, commodity code, customs value, origin, declarations, duty and VAT treatment with the customs agent.
4. Obtain comparable quotes
Compare the GBP required for the same USD net invoice amount, including all sending, intermediary and receiving fees.
5. Use dual approval
Independently confirm bank details using an established contact; one person prepares and another approves the payment.
6. Match payment to delivery
Keep the remittance advice, supplier acknowledgement, customs documents, inspection evidence and goods-received record together.
Assumptions
- A UK VAT-registered company buys goods from a genuine Chinese supplier under a USD-denominated contract.
- The invoice is exactly USD 240,000, with no recipient/intermediary deduction in the worked example.
- Illustrative quotes are 1.2400 and 1.2475 USD/GBP; each has a £25 fee payable in addition. Rates are assumptions, not market quotes.
- Freight, duty, insurance and import VAT are excluded from the transfer arithmetic and must be estimated separately.
- The goods, counterparties, beneficial owners, banks and route pass the applicable sanctions/export/import assessment.
Documents to gather
- Contract/purchase order and commercial invoice
- Supplier registration and beneficial-owner checks
- Independently verified beneficiary details
- Goods specification and inspection record
- EORI and customs-agent instructions
- Customs declaration and VAT evidence
- FX confirmation and payment approval trail
Tax and reporting questions
- Paying the foreign invoice does not complete UK import compliance. EORI, declarations, correct goods classification and any relevant licences must be assessed.
- Import VAT and duty are separate from the transfer price. Eligible VAT-registered businesses can use postponed VAT accounting subject to the rules; this affects cash flow, not whether VAT exists.
- UK sanctions can apply to UK companies worldwide. Screening needs to include ownership/control and transaction restrictions, not only an exact-name list check.
Risks
- Invoice-redirection fraud
- Goods not delivered or failing inspection
- Rate changes before later contract instalments
- Unbudgeted duty, VAT or shipping costs
- Incorrect assumptions about supplier-country export controls
Things we cannot know for you
- Goods classification and origin
- Current supplier-country export and bank requirements
- Incoterms and exact receiving-bank charges
When to bring in a professional
- Restricted or dual-use goods
- New supplier or an unusual third-party beneficiary
- Letters of credit, guarantees or hedging contracts
- Any sanctions/ownership match
- Unclear customs classification or VAT recovery
Educational example. Figures are assumptions, not a quote, tax ruling or guaranteed saving. Your facts and both countries’ rules matter.
My brief
Write down how this applies to you. It saves to your account as you type.
Sign in as a member to save this to your account.
Sources
- Using payment service providers, Financial Conduct Authority (checked 2026-11-05)
- AMLG11630: Source of Funds & Source of Wealth, HMRC (checked 2026-11-05)
- Import goods into the UK: step by step, UK Government / HMRC (checked 2026-11-05)
- Paying VAT on imports, HMRC (checked 2026-11-05)
- UK financial sanctions general guidance, Office of Financial Sanctions Implementation (checked 2026-11-05)
- How to check a firm or individual is authorised, Financial Conduct Authority (checked 2026-11-05)