UK property; onward destination unspecified · Illustrative example
Separate property-sale cash from the gain
Calculate the sale gain and the cash balance independently.
Money in
Property sale price: £1,200,000
Money out
Cash before tax and other costs: £830,000
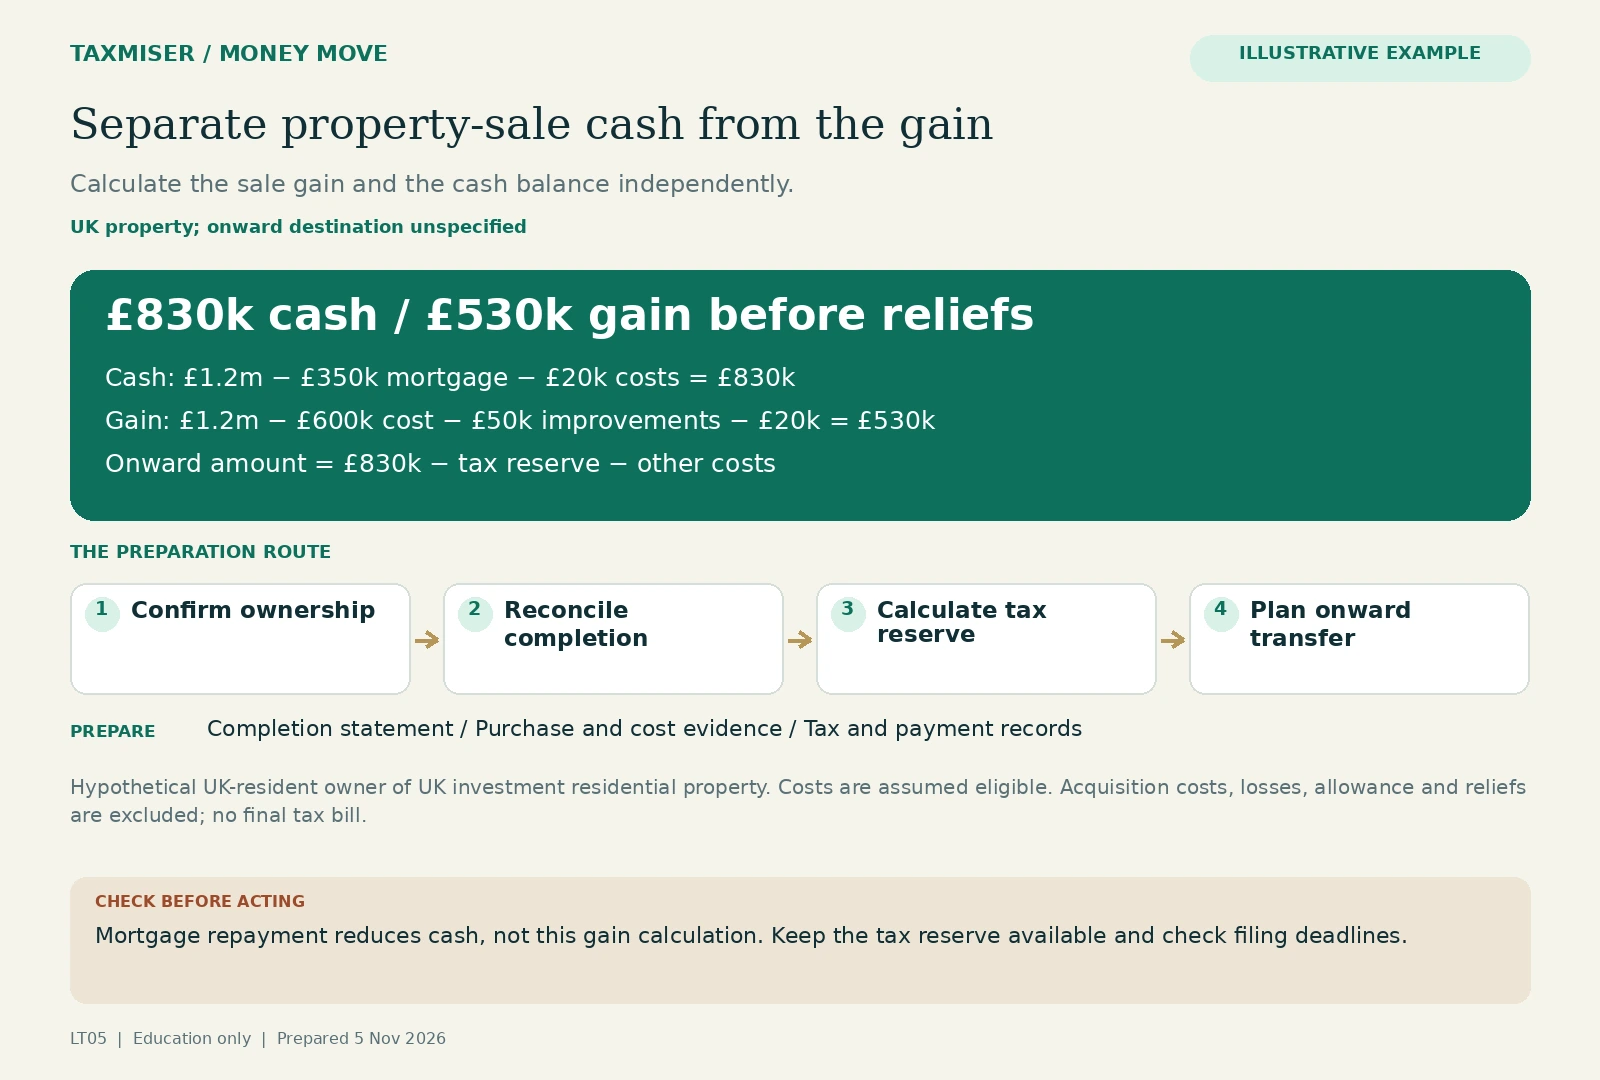
£830k cash / £530k gain before reliefs
- Cash: £1.2m − £350k mortgage − £20k costs = £830k
- Gain: £1.2m − £600k cost − £50k improvements − £20k = £530k
- Onward amount = £830k − tax reserve − other costs
Hypothetical UK-resident owner of UK investment residential property. Costs are assumed eligible. Acquisition costs, losses, allowance and reliefs are excluded; no final tax bill.
Mortgage repayment reduces cash, not this gain calculation. Keep the tax reserve available and check filing deadlines.
Step by step
1. Agree the ownership and tax facts
Confirm who owns the asset, residence, use of the property, acquisition history, relevant reliefs and completion date.
2. Reconcile the completion statement
Separate gross sale price, mortgage discharge, legal/agent fees and net bank receipt.
3. Calculate and reserve tax
Have the tax computation and payment deadline checked; keep the reserve liquid and in the correct ownership.
4. Assemble the proof
Keep the purchase/sale contracts, completion statement, qualifying cost invoices and solicitor/accountant correspondence.
5. Plan onward funds
Compare transfer costs and destination rules only for the amount available after liabilities. Explain the underlying sale to the provider.
6. Complete filings and reconcile
Record the filing/payment references and match the final onward transfer to the retained evidence.
Assumptions
- A UK-resident individual sells a personally owned UK investment residential property; no main-residence relief is assumed.
- Sale proceeds are £1,200,000; original qualifying purchase cost is £600,000; qualifying capital improvements are £50,000; selling costs are £20,000.
- The outstanding mortgage repaid at completion is £350,000. Acquisition costs, earlier losses, annual allowance and any relief are deliberately excluded.
- All assumed improvement/sale costs need documentary eligibility checks. The calculation is a gain illustration, not a final tax bill.
- The onward destination and tax residence after a move are not assumed. No amount is committed until the tax reserve is established.
Documents to gather
- Purchase and sale contracts
- Solicitor completion statement
- Mortgage redemption statement
- Qualifying improvement and transaction-cost invoices
- Tax calculation and filed return/payment evidence
- Proof of net proceeds received
- Onward FX/payment confirmations
Tax and reporting questions
- UK property gains use eligible acquisition, disposal and improvement costs; ordinary maintenance is different. The mortgage cash repayment should not be confused with the gain calculation.
- Any CGT due on this UK residential property sale generally must be reported and paid within 60 days of completion. Additional Self Assessment reporting can also be needed.
- A company selling its assets generally faces Corporation Tax. An individual selling company shares faces a separate CGT analysis. These are different legal owners and transactions.
- A business-exit article must not promise the old 10% BADR rate. Qualifying disposals from 6 April 2026 use 18%, with eligibility and lifetime-limit checks. No BADR saving is assumed here.
Risks
- Spending or transferring the tax reserve
- Wrong tax deadline
- Mixing sale proceeds and taxable gain
- Claiming ineligible improvement costs or relief
- Mistaking company cash for personal wealth
Things we cannot know for you
- Actual tax rate, allowance, losses and relief eligibility
- Beneficial ownership and property history
- Destination-country reporting
- Final settlement adjustments
When to bring in a professional
- Every substantial property/business disposal
- Non-UK residence or planned emigration
- Trust/company/joint ownership
- Earn-outs, rollover, deferred consideration or mixed-use property
- Any relief claim
Educational example. Figures are assumptions, not a quote, tax ruling or guaranteed saving. Your facts and both countries’ rules matter.
My brief
Write down how this applies to you. It saves to your account as you type.
Sign in as a member to save this to your account.
Sources
- Using payment service providers, Financial Conduct Authority (checked 2026-11-05)
- AMLG11630: Source of Funds & Source of Wealth, HMRC (checked 2026-11-05)
- Tax when you sell property: Work out your gain, HMRC (checked 2026-11-05)
- Report and pay Capital Gains Tax: If you sold a property in the UK, HMRC (checked 2026-11-05)
- CG50285: Issue of shares, subscription and purchase, HMRC (checked 2026-11-05)
- Corporation Tax when you sell business assets, HMRC (checked 2026-11-05)
- Business Asset Disposal Relief: Eligibility, HMRC (checked 2026-11-05)
- Tax when you sell shares, HMRC (checked 2026-11-05)